

South Korea's Sinokor Group Moves Nearly 40% of Hormuz Crude as Flows Rebound
Tankers controlled by South Korea's Sinokor Group transported nearly 40 percent of oil transiting the Strait of Hormuz in September as maritime flows picked up.
By The Global Wire Newsroom · Reported from The Business Times
Link preview · horizonglobalnews.com
South Korea's Sinokor Group Moves Nearly 40% of Hormuz Crude as Flows Rebound
Tankers controlled by South Korea's Sinokor Group transported nearly 40 percent of oil transiting the Strait of Hormuz in September as maritime flows picked up.
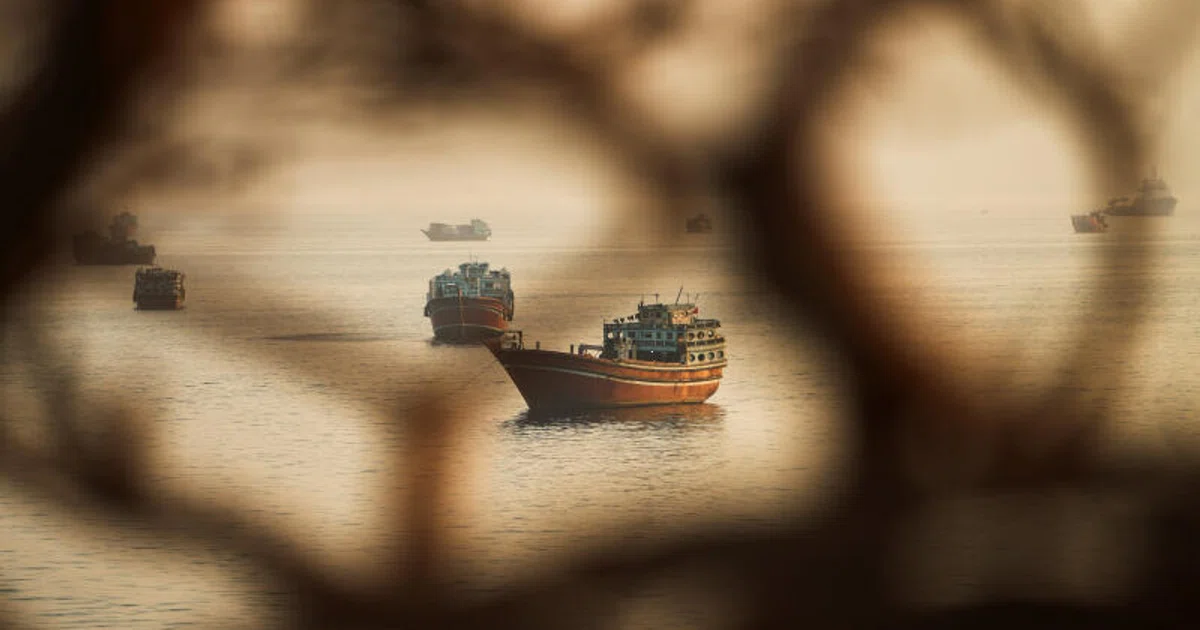
A privately held South Korean maritime conglomerate has emerged as the dominant carrier of crude moving through the Persian Gulf, handling an outsized portion of shipments through the world's most critical petroleum chokepoint. Tankers owned by Sinokor Merchant Marine Co. and its affiliates accounted for nearly 40 percent of all crude oil transiting the Strait of Hormuz during the month of September, according to tracking and industry data reported by The Business Times. The surge in Sinokor-managed liftings coincided with a broader rebound in Persian Gulf export volumes, highlighting how specialized private fleet operators can capture vast market share in high-stakes maritime corridors where geopolitical tension, insurance shifts, and shifting trade routes have reshuffled traditional tanker deployments.
Key facts
What happened
Maritime tracking data compiled for September revealed an extraordinary concentration of tanker tonnage under the control of a single private maritime group. As oil exports out of Persian Gulf terminals recovered from earlier volume fluctuations, tankers owned and operated by Seoul-based Sinokor Group moved close to 40 percent of the seaborne crude transiting outward through the Strait of Hormuz, as reported by The Business Times.
The volume moved by Sinokor vessels reflects a rapid operational scaling within the narrow waterway, which separates Iran from Oman and the United Arab Emirates. Over recent months, global crude markets have contended with shifting production quotas from the Organization of the Petroleum Exporting Countries (OPEC) and its partners, alongside volatile tanker freight rates and evolving risk premiums for vessels entering Gulf waters. As export terminals in Saudi Arabia, Iraq, Kuwait, and the United Arab Emirates loaded cargoes bound primarily for refineries in East Asia, Sinokor's vast pool of tonnage was systematically mobilized to meet charterer demand.
While major Western energy corporations and listed European tanker operators have at times adjusted their exposure to the Middle East Gulf in response to geopolitical escalations or chartering constraints, Sinokor has pursued an aggressive asset-acquisition strategy. By deploying a substantial portion of its Very Large Crude Carrier (VLCC) fleet into Middle Eastern liftings, the company captured market share that was previously dispersed among a broader roster of international shipowners, state-owned national tanker companies, and European commercial pools.
Why it matters
The emergence of a single company carrying nearly four out of every ten barrels leaving the Strait of Hormuz represents an unusual and consequential concentration of operational risk in the international energy supply chain. The Strait of Hormuz is widely regarded by energy economists and military planners as the single most critical chokepoint in the global economy. Approximately 20 to 21 million barrels of crude oil, condensate, and refined petroleum products move through its outbound shipping lanes every day under normal conditions, feeding major refining hubs in China, India, Japan, and South Korea. When shipping capacity through such a vital artery is concentrated in the hands of a few private operators, any commercial, regulatory, or operational disruption affecting that specific entity has amplified systemic repercussions.
From a market structure perspective, Sinokor's dominance illustrates the changing dynamics of the global tanker fleet. Over the past five years, the international tanker market has bifurcated. A substantial portion of older tonnage migrated to the so-called shadow or dark fleet to service sanctioned trade lanes involving Russia, Iran, and Venezuela. Concurrently, mainstream, compliant tonnage has faced shifting environmental regulations from the International Maritime Organization (IMO) and escalating scrutiny from maritime insurers. In this constrained environment, independent owners with deep balance sheets and expansive fleets wield unprecedented pricing power and commercial leverage over charterers who require compliant, high-capacity tonnage to move Middle Eastern barrels to Asian demand centers.
Furthermore, this development highlights the reliance of Asian economies on specific maritime logistics providers. South Korea, Japan, and Taiwan import virtually all of their crude oil, with more than 70 percent of their combined supply originating from Gulf producers. If an operator handling such a vast share of transits encounters financial strain, technical difficulties, or underwriting complications, the physical delivery schedules of Asian refiners could face immediate bottlenecks.
The background
Sinokor Merchant Marine Co., Ltd. was established in 1989, initially making its mark by launching the first regular direct container liner service between South Korea and mainland China even before the formal normalization of diplomatic ties between Seoul and Beijing in 1992. Over the subsequent three decades, the company evolved from an intra-Asian feeder container line into a diversified maritime giant under the low-profile leadership of its founder, Chung Tae-soon, who has also served as chairman of the Korea Shipowners' Association.
Throughout the late 2010s and early 2020s, while many Western public shipping companies refrained from ordering new crude carriers due to cyclical downturns and uncertainty over future maritime fuel standards, Sinokor engaged in counter-cyclical vessel procurement. The group acquired dozens of modern VLCCs—each capable of transporting up to 2 million barrels of crude—both through newbuilding orders at major South Korean shipyards such as HD Hyundai and Hanwha Ocean, and through opportunistic purchases on the secondhand market. These vessels typically operate under long-term bareboat or time charters, as well as spot-market fixtures arranged through global commodity trading houses and national oil companies.
Navigating the Strait of Hormuz has historically demanded robust insurance arrangements and sophisticated security protocols. The strait measures only 21 nautical miles wide at its narrowest point, with the inbound and outbound traffic separation scheme consisting of two-mile-wide channels separated by a two-mile buffer zone. Periodic regional flare-ups—ranging from the Tanker War of the 1980s to drone strikes, vessel boardings, and electronic navigation jamming in recent years—have periodically caused marine hull and machinery underwriters, as well as Protection and Indemnity (P&I) clubs, to impose war-risk additional premiums on voyages entering the Persian Gulf. Operators that maintain established insurance ties, high safety ratings, and acceptable compliance profiles can leverage these assets to dominate loading windows when regional output recovers.
Reaction
Neither Sinokor Group nor South Korean maritime regulators issued public statements detailing the commercial fixtures that led to the September milestone. Because Sinokor is an unlisted, privately held corporation, its management is not subject to the quarterly public earnings calls or immediate commercial disclosures required of listed competitors in New York, London, or Oslo.
Market observers, tanker brokers, and commodity analysts in Singapore, London, and Houston are closely monitoring the fixture logs to understand the contractual architecture supporting Sinokor's operations. Industry bodies, including the International Association of Independent Tanker Owners (INTERTANKO), have repeatedly underscored the necessity of open competition and vessel availability to maintain stability in global tanker freight markets. Regional authorities and naval task forces operating under the Combined Maritime Forces (CMF) and European-led maritime surveillance missions in the Strait of Hormuz routinely track vessel traffic density to ensure navigation freedom, though they maintain a policy of neutrality regarding commercial market shares.
Refiners and state procurement agencies across East Asia—particularly in Seoul and Tokyo—are expected to evaluate their reliance on concentrated chartering arrangements through their regular internal risk-management and supply-chain resilience reviews.
What we don't know yet
Several key dimensions of Sinokor's Hormuz operations remain unconfirmed by public disclosures. The reporting from The Business Times established the roughly 40 percent volume figure for September, but the specific breakdown of counterparties remains undisclosed. It is not publicly verified whether Sinokor was acting primarily under long-term time charters with Middle Eastern national oil companies such as Saudi Aramco, ADNOC, or Iraq's SOMO, or if the voyages were booked on the spot market by independent commodity trading houses and Asian refiners.
Additionally, it is unclear whether this market share represents a temporary clustering of voyage schedules or a sustained structural shift that continued into October and the final quarter of the year. The exact number of individual vessels deployed, their respective flags of registry, and the specific destination ports across Asia and Europe have not been detailed. Finally, the extent to which Sinokor utilized specialized risk mitigation tools, such as private maritime security details or non-standard insurance syndicates, remains unknown.
What to watch
The trajectory of Hormuz crude flows and Sinokor's standing in the market will hinge on several forthcoming milestones. First, market participants will review October and November tanker tracking data from commercial platforms such as Kpler, Vortexa, and Lloyd's List Intelligence to determine if Sinokor's 40 percent transit share was an anomaly of calendar timing or the beginning of a persistent consolidation.
Second, upcoming decisions by OPEC+ regarding production levels will directly dictate aggregate export volumes out of Gulf terminals. If member states restore previously curtailed crude production, total export volumes will expand, testing whether Sinokor possesses sufficient available tonnage to maintain such a high proportion of shipments.
Third, charter rates for the benchmark Middle East Gulf-to-China route (TD3C) assessed by the Baltic Exchange will indicate whether concentrated vessel ownership is influencing freight costs for Asian refiners. Finally, any regulatory developments from maritime authorities regarding flag-state oversight, carbon intensity indicators (CII), or regional war-risk insurance revisions will directly impact the cost structure and operational viability of large-scale tanker operations in the Persian Gulf.
This article includes reporting originally published by The Business Times.
How this story was produced
This report was written by The Global Wire newsroom from reporting first published by The Business Times. We verify the core facts against the original report, write our own account, and add the background and consequences a short wire item leaves out. Drafting is AI-assisted inside an editor-supervised pipeline, and every story is checked for accuracy of attribution, structure and duplication before it appears — full detail in our AI and funding disclosure.
Spotted an error? Tell us at corrections@horizonglobalnews.com and read our corrections policy or editorial standards.
Reader comments
Loading comments…