

Trump Administration Unveils Framework for Federal School Choice Program Set for January Launch
The Federal Scholarship Tax Credit will become the nation's first nationwide school choice program on Jan. 1, allowing donors to fund private education scholarships.
By The Global Wire Newsroom · Reported from Bianca Vázquez Toness
Link preview · horizonglobalnews.com
Trump Administration Unveils Framework for Federal School Choice Program Set for January Launch
The Federal Scholarship Tax Credit will become the nation's first nationwide school choice program on Jan. 1, allowing donors to fund private education scholarships.
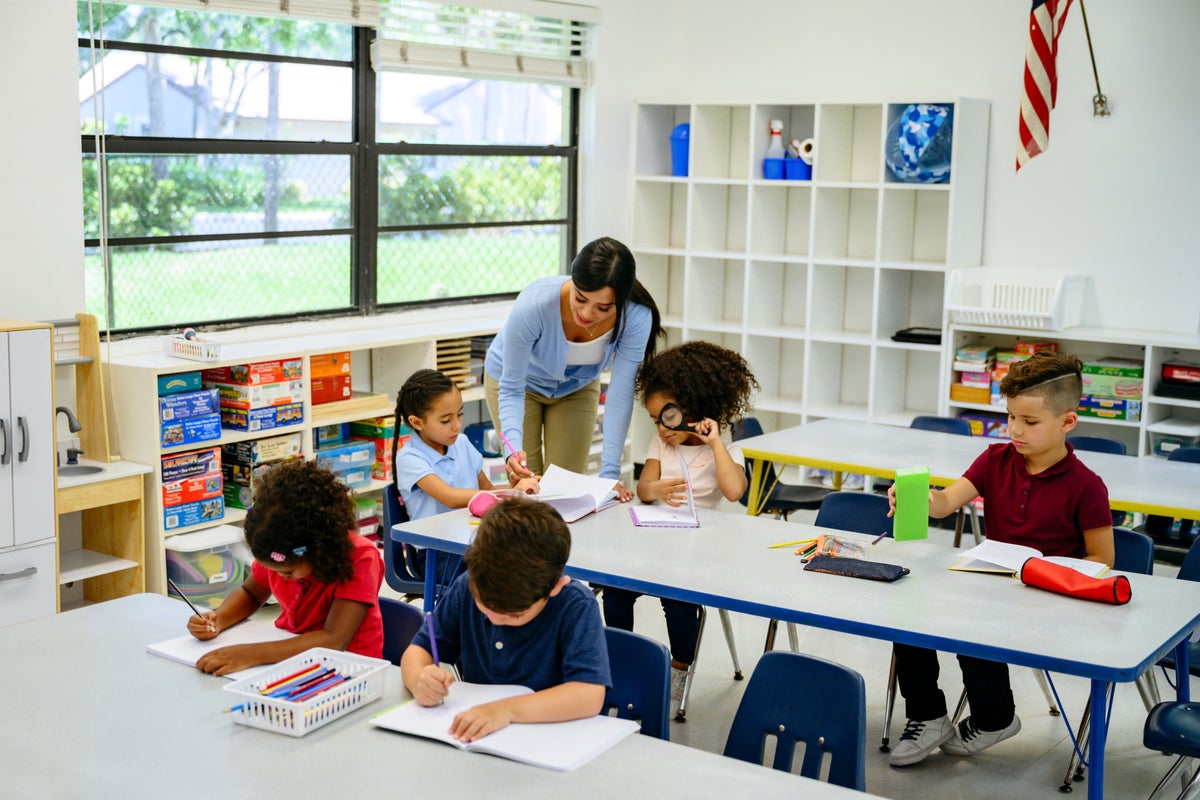
The Trump administration has released new operational details for the Federal Scholarship Tax Credit, establishing the first nationwide school choice program in United States history ahead of its scheduled implementation on January 1. Announced on October 1, 2026, the administrative update clarifies how the federal tax code will be leveraged to incentivize private contributions toward elementary and secondary school tuition scholarships. Under the initiative, individuals and corporations will be eligible for federal tax credits in exchange for voluntary donations made to approved scholarship-granting organizations. These non-profit entities will then distribute funds to cover tuition, fees, and related educational costs for students attending private, charter, parochial, or non-traditional learning institutions across all 50 states.
Key facts
What happened
On October 1, 2026, federal officials released long-awaited administrative details outlining how the Federal Scholarship Tax Credit will function when it takes effect on January 1. The program operates through a indirect funding model designed to bypass direct federal spending on non-public education. Under the framework, private donors—including individual taxpayers and corporate entities—can contribute capital to accredited, tax-exempt scholarship-granting organizations (SGOs). In return, these contributors earn credits against their federal tax liabilities, reducing what they owe to the U.S. Treasury.
The certified SGOs are responsible for managing the donated capital and evaluating student applications based on program criteria. Students awarded scholarships can apply the financial assistance toward private school tuition, religious school expenses, tutoring, standardized testing fees, special education services, and specialized instructional curricula. The new details outline federal reporting mandates, donor credit caps, application timelines, and accounting standards that non-profit organizations must meet to participate in the program.
By routing funds through private non-profit intermediaries rather than issuing direct federal vouchers or checks from the Department of Education, the administration aims to create a self-sustaining funding ecosystem for alternative education options while maintaining compliance with existing federal tax statutes.
Why it matters
The launch of a federal school choice program marks a monumental pivot in American educational policy, shifting the locus of education governance from state legislatures and local school boards toward federal tax policy. Historically, education in the United States has been primarily funded and governed by state and local authorities, with federal funding comprising a relatively small portion of overall public K-12 spending—typically focused on low-income schools and special education services.
For families, the Federal Scholarship Tax Credit lowers the financial barrier to private, parochial, and alternative education models, particularly in states that have not enacted statewide education savings accounts or voucher programs. Proponents argue that introducing consumer choice into primary and secondary education fosters competition, prompting public school systems to innovate while allowing students in underperforming school districts to seek better opportunities.
Conversely, public school advocates and education policy analysts argue that tax credit programs undermine public education systems by reducing overall federal tax revenues and encouraging students to exit traditional public schools. Because public school district funding models are frequently tied to enrollment figures, student departures can lead to reductions in state and local formula funding, forcing districts to consolidate services or trim instructional budgets. Additionally, critics point out that tax credits primarily benefit high-income donors who utilize tax planning strategies to offset substantial federal tax burdens.
The background
School choice policies have expanded significantly across the United States over the past three decades, evolving from targeted voucher programs in cities like Milwaukee and Cleveland into statewide initiatives. Tax credit scholarships were pioneered at the state level in the late 1990s and early 2000s, with states like Arizona, Florida, Pennsylvania, and Georgia establishing mechanisms that offered state tax credits for contributions to tuition funds.
Unlike traditional vouchers, which draw directly from state general revenue funds to pay private school tuition, tax credit scholarship models rely on private voluntary contributions incentivized by tax relief. This legal distinction has repeatedly shielded tax credit scholarship programs from legal challenges under state constitutional provisions—often referred to as Blaine Amendments—that prohibit public funds from being spent on religious institutions.
At the federal level, attempts to pass school choice legislation have stalled for decades due to partisan disagreement and constitutional debates regarding federalism and church-state separation. During the first Trump administration, then-Secretary of Education Betsy DeVos championed a national $5 billion tax-credit scholarship proposal known as the Education Freedom Scholarships and Opportunity Act, though it failed to gain necessary traction in Congress. Subsequent legislative proposals, including the Educational Choice for Children Act, sought to establish a similar federal tax-credit mechanism under Title 26 of the United States Code.
The broader legal landscape for private school choice was reshaped by key Supreme Court decisions, including *Espinoza v. Montana Department of Revenue* (2020) and *Carson v. Makin* (2022), which ruled that states offering public aid or tax incentives for private education cannot exclude religious schools simply because of their religious status or curriculum. These precedents cleared the legal path for nationwide programs that include faith-based institutions.
Reaction
Reaction to the administration's detailed framework has been split along established political and educational philosophy lines. Advocacy organizations supporting educational freedom, such as the American Federation for Children, EdChoice, and the Heritage Foundation, praised the announcement as a historic milestone for parental rights and educational equity, emphasizing that the program will expand opportunities for children whose local public schools do not meet their needs.
Conversely, major public education associations, including the National Education Association (NEA) and the American Federation of Teachers (AFT), strongly criticized the implementation details. Public school advocacy groups contend that federal tax credits represent a back-door voucher scheme that diverts critical financial support away from public school districts serving the vast majority of American students. Legal advocacy organizations, such as Americans United for Separation of Church and State and the American Civil Liberties Union (ACLU), are expected to scrutinize the regulatory rules for potential violations of federal administrative law or constitutional protections regarding public funding of religious instruction.
State education leaders have also expressed varying views. Governors in states with robust existing school choice programs welcomed the federal overlay, while education superintendents in states relying heavily on traditional public school funding models voiced concern regarding potential administrative confusion and shifting enrollment patterns.
What we don't know yet
Despite the release of the operational details, several critical operational and financial variables remain unresolved ahead of the January 1 launch. It remains unclear precisely how many scholarship-granting organizations will receive federal certification prior to the effective date, which could limit immediate geographic access for interested families during the initial application cycle.
Additionally, the reporting leaves open questions regarding how the federal tax credit will interact with existing state-level tax credit scholarship programs. It is currently uncertain whether donors will be permitted to stack state and federal tax credits for the same contribution, or whether federal regulations will impose income-eligibility caps on student applicants to prioritize lower-income families.
Furthermore, the long-term impact on federal Treasury revenue remains difficult to quantify without final annual caps on overall credit allocations, leaving fiscal policy experts uncertain about the net impact on the national deficit.
What to watch
As the January 1 launch date approaches, several specific benchmarks will indicate how effectively the program moves from policy formulation to execution:
Reporting for this article was based on original coverage provided by journalist Bianca Vázquez Toness.
How this story was produced
This report was written by The Global Wire newsroom from reporting first published by Bianca Vázquez Toness. We verify the core facts against the original report, write our own account, and add the background and consequences a short wire item leaves out. Drafting is AI-assisted inside an editor-supervised pipeline, and every story is checked for accuracy of attribution, structure and duplication before it appears — full detail in our AI and funding disclosure.
Spotted an error? Tell us at corrections@horizonglobalnews.com and read our corrections policy or editorial standards.
Reader comments
Loading comments…