

UK and Offshore Network Tied to €8bn in Annual EU Corporate Tax Losses, Study Finds
The Tax Justice Network estimates EU nations lose nearly €60bn annually to profit shifting, with British jurisdictions driving a substantial portion even as the UK suffers steep losses itself.
By The Global Wire Newsroom · Reported from Servet Yanatma
Link preview · horizonglobalnews.com
UK and Offshore Network Tied to €8bn in Annual EU Corporate Tax Losses, Study Finds
The Tax Justice Network estimates EU nations lose nearly €60bn annually to profit shifting, with British jurisdictions driving a substantial portion even as the UK suffers steep losses itself.
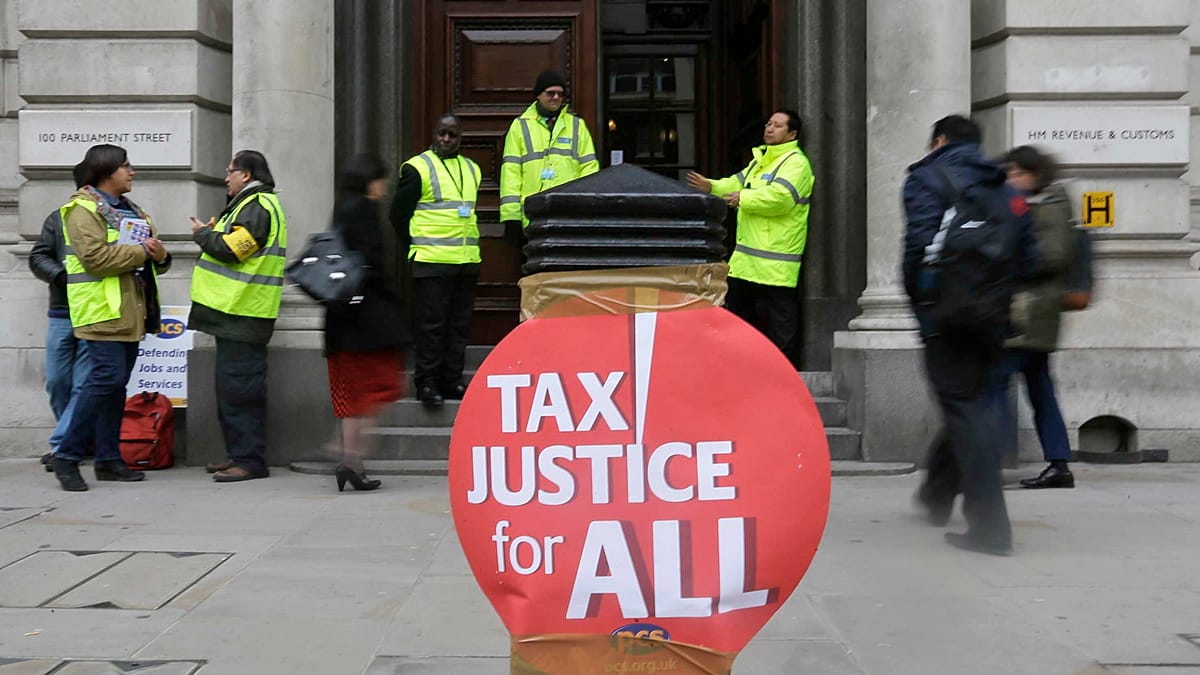
Member states of the European Union lose nearly €60 billion each year to cross-border corporate profit shifting, with approximately €8 billion of those losses linked directly to the United Kingdom and its satellite network of offshore financial centers, according to an analysis by the advocacy and research organization Tax Justice Network. The data underscores an entrenched structural paradox in global taxation: even as British jurisdictions function as a primary conduit for diverting revenue away from European public treasuries, the UK itself ranks among the heaviest net losers from multinational tax avoidance globally.
Key facts
What happened
According to reporting by Servet Yanatma, new calculations by the Tax Justice Network indicate that the European Union continues to experience deep erosions of its corporate tax base, surrendering close to €60 billion in potential annual revenue to multinational profit-allocation strategies. Of that total, roughly €8 billion is traced to the United Kingdom and the offshore financial centers operating under the British Crown.
Corporate profit shifting involves moving earnings generated in high-tax jurisdictions—where real economic activity, sales, and employment occur—to subsidiaries located in jurisdictions with nominal or zero corporate tax regimes. These transfers are typically executed through intra-group transactions, including royalty payments for intellectual property, management consultancy fees, cross-border corporate lending with inflated interest rates, and specialized transfer pricing structures. While the core transactions are designed to comply with existing legal frameworks, their primary function is to suppress tax liabilities in the jurisdictions where products and services are consumed.
In the Tax Justice Network's assessment, the UK's financial infrastructure does not operate in isolation. Rather, it functions at the center of an interconnected corporate services web encompassing the City of London alongside the Crown Dependencies—comprising Jersey, Guernsey, and the Isle of Man—and British Overseas Territories, notably the Cayman Islands, the British Virgin Islands, and Bermuda. This network provides legal structures, corporate secrecy provisions, trust arrangements, and specialized investment holding regimes that facilitate the routing of corporate capital away from sovereign treasuries, including those across the 27 EU member states.
Concurrently, the data illustrates that the UK's domestic fiscal system remains highly vulnerable to the very practices its broader jurisdiction facilitates. Multinational firms systematically shift earnings away from mainland Britain to alternative low-tax hubs in Europe, the Caribbean, and Asia, cementing the UK's position among the nations sustaining the highest gross financial damages from international tax gamesmanship.
Why it matters
The annual siphoning of €60 billion from European Union public treasuries represents a structural drain on sovereign budgets at a time of severe fiscal constraint across the continent. For public sector authorities, corporate tax revenues provide vital non-debt funding for healthcare systems, transportation networks, defense investments, educational infrastructure, and the multi-trillion-euro transition toward decarbonized energy grids. When multinational enterprises minimize their fiscal contributions through financial re-routing, governments face a zero-sum fiscal dilemma: cut statutory expenditures, increase borrowing on sovereign bond markets, or compensate for shortfalls by shifting the broader tax burden onto immovable bases, principally domestic labor and consumer consumption taxes such as Value Added Tax (VAT).
Beyond immediate budgetary shortfalls, systemic corporate profit shifting distorts economic competition and degrades market fairness. Small and medium-sized enterprises (SMEs)—which account for the vast majority of private employment across the EU—rarely possess the cross-border footprint, legal machinery, or capital resources required to maintain multi-jurisdictional tax mitigation structures. As a consequence, domestic businesses often pay statutory corporate income tax rates ranging from 15% to over 30%, while multinational competitors utilize conduit entities to achieve effective tax rates in the low single digits. This structural disparity suppresses domestic entrepreneurial competition, concentrates market share within multinational conglomerates, and undermines citizen confidence in the fairness and integrity of national revenue systems.
For the UK, the dual status as a major facilitator and a primary victim of international profit diversion highlights the internal contradictions of its post-imperial economic model. While the City of London and its offshore satellites capture fees from administration, legal structuring, and asset servicing, the mainland British Treasury forfeits billions of pounds in direct corporate levies, aggravating domestic budgetary deficits.
The background
Efforts to police multinational tax avoidance have challenged sovereign governments since the inception of cross-border corporate taxation in the early 20th century. For decades, international tax law relied on bilateral double taxation treaties based on standards originally devised by the League of Nations. These treaties were designed primarily to avoid subjecting corporate profits to multiple national levies, operating on the presumption that transactions between related subsidiaries would mirror independent transactions conducted at arm's length.
With the expansion of digital commerce, intellectual property valuation, and financialized service industries over the past three decades, multinational companies found it increasingly simple to relocate profit-generating intangible assets—such as algorithms, trademarks, and patents—to low-tax jurisdictions, regardless of where software engineers, factories, or end consumers were located.
In response to mounting public scrutiny following the 2008 global financial crisis, the G20 tasked the OECD with creating the Base Erosion and Profit Shifting (BEPS) initiative in 2013. The program yielded 15 specific action items designed to curtail aggressive transfer pricing, enforce country-by-country corporate reporting to tax authorities, and eliminate hybrid mismatch arrangements. In October 2021, an expanded coalition of nearly 140 jurisdictions under the OECD/G20 Inclusive Framework agreed to a historic two-pillar reform package. Pillar One aimed to reallocate taxation rights over the largest multinationals to market countries, while Pillar Two instituted a global minimum corporate tax rate of 15% on multinational enterprises with annual consolidated revenues exceeding €750 million.
The European Union took early steps to codify these principles through successive Anti-Tax Avoidance Directives (ATAD 1 and ATAD 2) and formally adopted the EU Minimum Tax Directive in December 2022 to transpose the 15% Pillar Two framework into member state law starting in 2024. Additionally, the European Commission established the EU list of non-cooperative jurisdictions for tax purposes, commonly known as the tax haven blacklist. However, EU anti-avoidance policies have historically faced institutional hurdles: taxation measures within the Council of the European Union require unanimous consent among all member states, granting individual low-tax EU jurisdictions legislative veto power over binding harmonized tax rules.
Reaction
The findings are set to draw immediate attention from public finance advocacy groups, legislative tax committees, and international transparency watchdogs. Civic organizations like the Tax Justice Network have long argued that voluntary compliance and piecemeal reforms are inadequate, advocating instead for unitary taxation systems where multinational enterprises are taxed as single global entities, with corporate profits apportioned to countries based on formulas measuring sales, assets, and payroll.
In European legislative corridors, the data is expected to fuel debate within the European Parliament's Subcommittee on Tax Matters (FISC) and the Committee on Economic and Monetary Affairs (ECON). Lawmakers pushing for tighter anti-avoidance measures routinely press the European Commission to confront offshore financial centers that retain close links to neighboring non-EU partners. Within the Council of the European Union, the figures provide leverage for higher-tax jurisdictions seeking to accelerate the implementation of defensive tax measures against uncooperative third-country jurisdictions.
Conversely, representative bodies from the British financial services industry and offshore legal sectors consistently defend their practices. Industry associations across the Crown Dependencies and British Overseas Territories maintain that their jurisdictions operate fully in compliance with international regulatory standards, exchange tax data automatically under the OECD's Common Reporting Standard (CRS), and should not be mischaracterized as conduits for illicit financial flows. Official representatives typically stress that offshore centers provide vital global liquidity, support foreign direct investment, and operate within the bounds of international law.
What we don't know yet
While the headline figures establish the broad scale of the revenue losses, significant details regarding the underlying methodology and distribution remain unspecified in the initial report. The summary provided by Servet Yanatma does not enumerate the exact breakdown of losses incurred by individual EU member states, leaving it unclear whether major European economies—such as Germany, France, and Italy—absorb the bulk of the €8 billion UK-linked drain, or if smaller member states sustain disproportionate per capita losses.
Furthermore, the initial reporting leaves unaddressed which specific corporate sectors—such as consumer technology, pharmaceutical patents, fossil fuels, or cross-border retail—account for the largest shares of diverted capital. Crucially, it remains to be verified to what extent these estimates capture corporate behaviors postdating the entry into force of Pillar Two's 15% minimum corporate tax, which began phased implementation across European jurisdictions and the UK in 2024. Because corporate tax filings and official administrative audits frequently experience reporting lags of two to three years, contemporary estimates often reflect structural dynamics that predate the full enforcement of the newest international standards.
What to watch
Key policy milestones and regulatory reviews in the months ahead will determine whether governments can successfully stem the fiscal drain documented by the Tax Justice Network. Foremost among these is the publication of comprehensive national revenue audits examining the operational impact of the OECD's Pillar Two minimum tax regime across both the EU and the UK. Analysts will look for concrete evidence showing whether the 15% global minimum rate has measurably flattened cross-border profit shifting or merely prompted corporations to restructure intangible assets through alternative accounting mechanisms.
At the European Union level, observers should monitor upcoming revisions to the EU list of non-cooperative jurisdictions by the Code of Conduct Group on Business Taxation. While British Overseas Territories have periodically faced scrutiny from Brussels, political and diplomatic considerations have often shielded them from direct punitive blacklisting. Any renewed push by European lawmakers to impose withholding taxes or deny treaty benefits to transactions routed through British offshore territories will represent a significant escalation in post-Brexit financial friction.
Finally, developments within the UK parliament warrant careful attention. Westminster lawmakers continue to face sustained domestic and international pressure to enforce publicly accessible beneficial ownership registers across all British Overseas Territories. Progress on these statutory registers, coupled with bilateral financial dialogue under the EU-UK Trade and Cooperation Agreement (TCA), will signal whether London and Brussels will deepen administrative collaboration against tax base erosion or allow cross-Channel tax competition to persist.
This article includes reporting originally published by Servet Yanatma.
How this story was produced
This report was written by The Global Wire newsroom from reporting first published by Servet Yanatma. We verify the core facts against the original report, write our own account, and add the background and consequences a short wire item leaves out. Drafting is AI-assisted inside an editor-supervised pipeline, and every story is checked for accuracy of attribution, structure and duplication before it appears — full detail in our AI and funding disclosure.
Spotted an error? Tell us at corrections@horizonglobalnews.com and read our corrections policy or editorial standards.


Reader comments
Loading comments…