

French Output Contracts in Third Quarter as Budget Deadlock Deepens Recession Fears
France recorded a 0.1 percent GDP contraction in the third quarter amid flatline growth across 2026, intensifying fiscal pressure as lawmakers debate spending plans.
By The Global Wire Newsroom · Reported from Alexander Kazakevich
Link preview · horizonglobalnews.com
French Output Contracts in Third Quarter as Budget Deadlock Deepens Recession Fears
France recorded a 0.1 percent GDP contraction in the third quarter amid flatline growth across 2026, intensifying fiscal pressure as lawmakers debate spending plans.
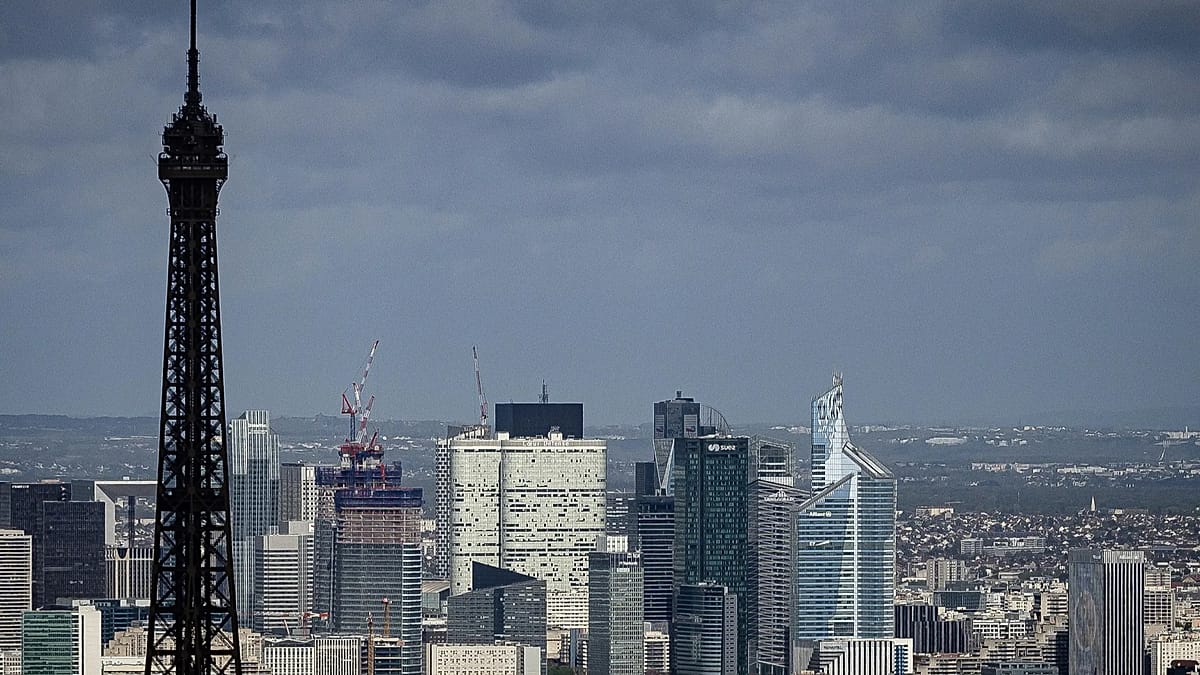
PARIS — France’s economy stalled over the first nine months of the year, culminating in a 0.1 percent contraction in gross domestic product between July and September, according to economic reporting by Alexander Kazakevich. The downturn places the eurozone’s second-largest economy on the brink of a technical recession and compounds pressure on the government in Paris, which is currently attempting to rally a fragmented parliament behind its fiscal blueprint for 2027. With national output failing to expand since January, the contraction threatens to widen the country's public deficit and raises acute questions among European regulators and sovereign debt investors regarding the credibility of French fiscal management.
Key facts
What happened
France’s national output plateaued across the opening half of the year before shifting into negative territory during the summer months. Data covering the third quarter revealed that gross domestic product shrank by 0.1 percent, eliminating any residual gains from the prior periods and leaving net economic expansion across the entirety of the year at zero, according to reporting by Alexander Kazakevich.
The slowdown reflects broad-based domestic headwinds. Throughout the July-to-September window, business investment softened and consumer purchasing appetite remained constrained under the weight of sustained borrowing costs and household caution. While international trade and public expenditure historically provided counterweights during periods of weak private sector activity, neither sector delivered sufficient momentum to avert the quarterly contraction.
Compounding this underlying economic weakness is an unsettled legislative environment in Paris. The administration has struggled to build a stable parliamentary majority to secure passage of its upcoming budget for 2027. Lawmakers across rival political formations remain sharply divided over tax policy, entitlement spending, and civil service outlays. Because tax receipts inevitably track macroeconomic performance, the abrupt loss of output directly imperils the government's fiscal baseline, leaving ministers with diminishing fiscal headroom as they attempt to reconcile austerity measures demanded by debt markets with social spending demands from legislative opponents.
Why it matters
The immediate consequence of a stalling French economy is an erosion of sovereign fiscal targets. Modern state budgets rely heavily on projected nominal GDP expansion to support revenue collection from value-added tax, corporate profits, and payroll levies. When real output contracts by 0.1 percent and exhibits zero cumulative growth across three quarters, tax receipts fall short of administrative targets while automatic stabilizers, such as unemployment assistance and social safety net outlays, naturally escalate. This dynamic widens the nominal budget deficit without any discretionary spending increases.
Beyond domestic tax coffers, the contraction carries systemic implications for the broader euro currency union. France represents roughly one-fifth of total economic output inside the 20-nation single currency area. Prolonged stagnation in Paris directly depresses cross-border supply chains, curbing demand for manufactured goods and commercial services from core trading partners, notably Germany, Italy, and Spain. A weaker French growth trajectory also complicates monetary policy calculations for the European Central Bank in Frankfurt, which must balance the risks of entrenched disinflation or stagnation in Western Europe against price stability mandates.
For financial markets, fiscal ambiguity in a sovereign sovereign borrower with high debt burdens translates into wider risk premiums. Investors evaluate French sovereign bonds, known as Obligations Assimilables du Trésor (OATs), relative to ultra-safe German federal debt (Bunds). The spread between ten-year French and German borrowing costs acts as a direct barometer of market confidence in Paris. If international rating agencies conclude that economic inertia will impede structural deficit reduction, downgrades could follow, raising debt-servicing expenses across the entire French public sector and private banking system.
The background
France’s current economic predicament is rooted in both structural post-pandemic imbalances and shifting European fiscal governance. Following the global coronavirus crisis and the energy shock precipitated by Russia’s full-scale invasion of Ukraine in 2022, France deployed expansive state subsidies—frequently termed the "whatever the cost" doctrine—to shield domestic households and businesses from sudden utility spikes. While this aggressive state intervention cushioned the immediate downturn, it drove public debt past 110 percent of GDP and left annual fiscal deficits substantially above the European Union’s 3 percent threshold.
Under the reformed European Union fiscal framework, enforced by the European Commission under the Stability and Growth Pact, member states running structural deficits above 3 percent of output or debt-to-GDP ratios exceeding 60 percent face formal disciplinary mechanisms, known as the Excessive Deficit Procedure. France was formally placed under this corrective framework alongside several other European peers, obligating Paris to implement binding multi-year adjustments to steadily curb structural spending.
Complicating these obligations is the balance of power inside the French National Assembly, the lower house of parliament. Lacking an outright legislative majority, any governing coalition must navigate a fractured chamber split among a centrist presidential alliance, a broad leftist bloc resistant to spending reductions, and a nationalist right skeptical of European budgetary constraints. Under the French Constitution, governments can invoke special constitutional mechanisms, notably Article 49.3, to enact budgetary legislation without an affirmative parliamentary vote. However, exercising that executive power automatically exposes the sitting administration to motions of no confidence, introducing perpetual political fragility.
In previous decades, France relied on relatively robust internal consumer spending to cushion downturns that struck export-oriented economies like Germany. The persistence of flatline growth throughout the current calendar year marks a departure from that historical resilience, underscoring systemic fatigue in domestic consumption, rising corporate insolvencies, and prolonged reluctance among businesses to commit capital amid shifting legislative ground rules.
Reaction
While the primary reporting by Alexander Kazakevich notes the government’s urgent campaign to persuade political factions to back the 2027 fiscal plan, formal public declarations from political leadership and international institutions remain pending as national accounts are digested. The executive branch has historically argued that fiscal discipline and supply-side reforms are indispensable to preserve sovereign financial credibility and prevent a punitive rise in debt service costs.
Opposition leaders inside the National Assembly are anticipated to use the 0.1 percent contraction to argue that the executive branch's fiscal strategy is actively choking off economic dynamism. Left-wing factions routinely advocate for higher corporate windfall taxes, public investment in infrastructure, and the preservation of social entitlements to stimulate household demand from the bottom up. Conversely, conservative and right-wing blocs have demanded steep spending reductions targeting administrative bureaucracy and social expenditures, while rejecting income and corporate tax increases that they argue erode international competitiveness.
In Brussels, officials at the European Commission’s Directorate-General for Economic and Financial Affairs are expected to scrutinize the French performance as part of their regular budgetary assessments under the Excessive Deficit Procedure. International credit rating agencies, including S&P Global Ratings, Moody’s, and Fitch Ratings, likewise monitor these figures closely ahead of scheduled sovereign rating reviews, where any sovereign downgrade could immediately reverberate through sovereign bond pricing.
What we don't know yet
The reporting does not detail the microeconomic breakdown of the third-quarter contraction, leaving it uncertain whether the downturn was driven primarily by a slump in private capital expenditure, an inventory drawdown by manufacturers, or a decline in household consumption. Clarification from official statistical authorities will be necessary to determine which specific industries suffered the steepest retrenchment and whether export volumes provided any offset.
It is also unclear what baseline assumptions the government used when drafting the proposed 2027 budget. If statutory spending targets were predicated on an assumed growth rate of 0.5 percent or higher, the current trajectory will force ministers to present emergency fiscal revisions, either through deeper spending cuts or revenue-raising measures. Crucially, the reporting leaves open how the government intends to surmount the parliamentary impasse—specifically, whether ministers will attempt to negotiate compromises across party lines or risk a confidence vote by employing constitutional decree powers.
What to watch
Several upcoming milestones will clarify the path ahead for the French economy and its public finances:
This report incorporates news reporting by Alexander Kazakevich on France’s third-quarter economic contraction, cumulative year-to-date output performance, and ongoing budgetary negotiations.
How this story was produced
This report was written by The Global Wire newsroom from reporting first published by Alexander Kazakevich. We verify the core facts against the original report, write our own account, and add the background and consequences a short wire item leaves out. Drafting is AI-assisted inside an editor-supervised pipeline, and every story is checked for accuracy of attribution, structure and duplication before it appears — full detail in our AI and funding disclosure.
Spotted an error? Tell us at corrections@horizonglobalnews.com and read our corrections policy or editorial standards.

Reader comments
Loading comments…