

Asian Equities Fall as AI Tech Debt Issuance and Rising Oil Strain Bond Markets
Asian stock indexes dropped as corporate debt sales for artificial intelligence infrastructure joined rising crude oil prices to pressure sovereign bond yields and tighten capital competition.
By The Global Wire Newsroom · Reported from CNA
Link preview · horizonglobalnews.com
Asian Equities Fall as AI Tech Debt Issuance and Rising Oil Strain Bond Markets
Asian stock indexes dropped as corporate debt sales for artificial intelligence infrastructure joined rising crude oil prices to pressure sovereign bond yields and tighten capital competition.
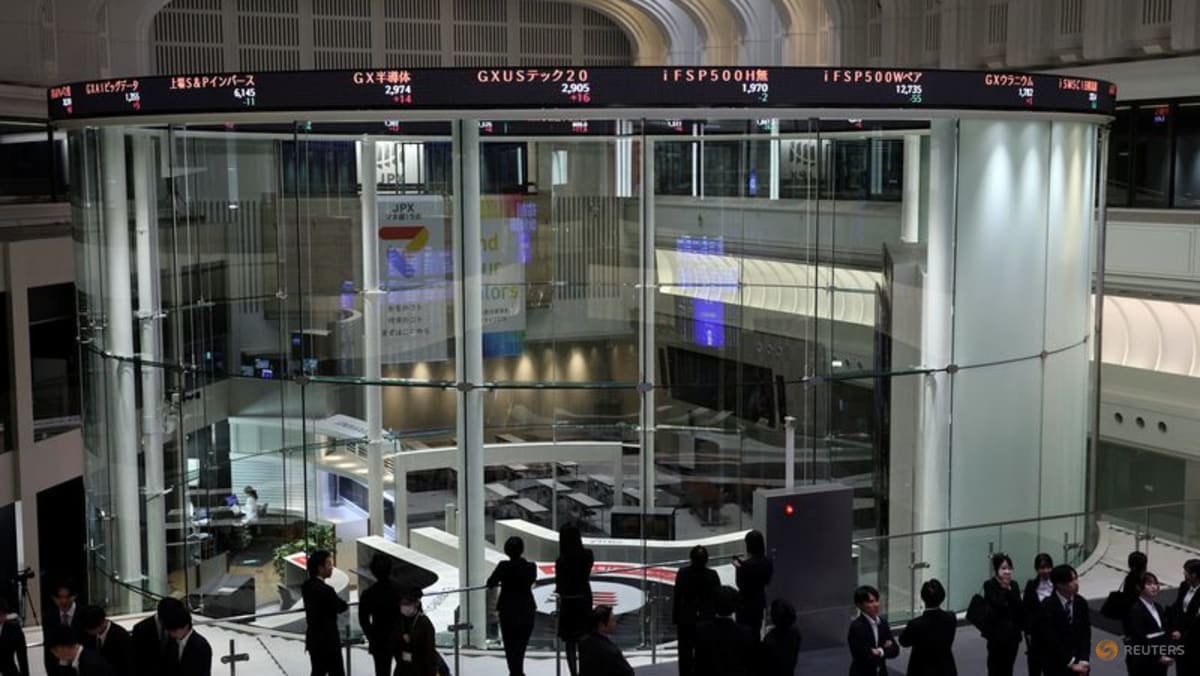
Asian stock markets experienced broad selling pressure on Thursday, Oct. 8, 2026, as sovereign bond yields climbed under the combined strain of rising energy costs and massive prospective debt offerings from technology conglomerates. Investors across major regional exchanges retreated amid growing competition for institutional capital, driven by reports that leading technology corporations are preparing multi-billion-dollar bond sales to fund artificial intelligence capital expenditures. The influx of high-yield corporate paper has begun directly crowding out sovereign debt instruments, compounding pressure on U.S. Treasuries and regional benchmark bonds at a time when renewed gains in global crude oil prices have reignited worries over persistent inflation.
Key facts
What happened
Trading across major Asian equity hubs opened on a defensive note on Oct. 8, with stock benchmarks declining as fixed-income market volatility spilled over into broader asset classes. According to market reporting by CNA, fixed-income markets became the primary driver of broader market weakness after reports surfaced indicating that several of the world's largest technology corporations are preparing to enter the primary corporate debt market with multi-billion-dollar bond offerings. The capital sought by these technology firms is designated for high-density data center construction, specialized semiconductor acquisition, and long-term energy supply contracts necessary to expand artificial intelligence computing capacity.
The prospective arrival of such significant corporate bond supply triggered an immediate reaction across global debt markets. Institutional portfolio managers began adjusting their asset holdings, freeing up liquidity to absorb high-grade corporate paper that typically offers attractive yield spreads over sovereign debt. This reallocation of capital created direct selling pressure on government securities, driving yields higher across benchmark maturities in Asia and the United States.
Compounding the pressure on fixed-income instruments was a sustained advance in global crude oil prices. Energy markets pushed higher during recent sessions, raising concerns among fixed-income traders that headline inflation rates could remain sticky or accelerate in upcoming quarters. Because higher energy prices diminish the real return on fixed-coupon debt, bond traders sold off sovereign paper, pushing sovereign yields up further.
In the U.S. Treasury market, benchmark bond prices sagged under the combined weight of potential private sector supply and energy-driven inflation risks. Although government debt auctions had previously demonstrated baseline demand from institutional buyers, the prospect of competing directly against high-grade technology bonds forced sovereign debt yields higher as markets sought a new equilibrium price for fixed-income risk.
Why it matters
The intersection of massive corporate borrowing for artificial intelligence infrastructure and rising sovereign debt yields represents a significant shift in global capital allocation dynamics. Historically, major technology companies operated with vast net-cash balance sheets, self-funding capital investments out of operational cash flow. The transition toward multi-billion-dollar debt issuances demonstrates the unprecedented capital intensity required to build, cool, and power next-generation artificial intelligence infrastructure. When corporate entities issue debt on a scale traditionally reserved for sovereign nations or supranational institutions, they actively compete with government treasuries for limited institutional investment liquidity.
For sovereign issuers, this competition comes at a challenging time. Major governments around the globe are already managing substantial debt burdens and elevated budget deficits. When sovereign paper must compete against corporate debt offering premium spreads from balance-sheet-healthy technology giants, sovereign borrowing costs inevitably rise. Higher government bond yields elevate benchmark interest rates throughout the economy, directly influencing commercial loan pricing, mortgage rates, and corporate refinancing costs across all industrial sectors.
Furthermore, the simultaneous rise in crude oil prices complicates the monetary policy landscape for central banks. Monetary authorities in both developed and emerging markets have been seeking to normalize interest rate policy after years of combatting post-pandemic inflation. Renewed energy price inflation threatens to delay planned interest rate cuts or force central banks to maintain restrictive monetary stances for longer than financial markets had priced in. For equity markets, higher risk-free bond yields reduce the net present value of future corporate earnings, creating a valuation drag that disproportionately impacts high-valuation growth stocks and interest-rate-sensitive sectors such as real estate and utilities.
The background
The structural dynamics of global fixed-income markets have evolved significantly over recent years. Following the extraordinary fiscal spending and monetary stimulus deployed during the COVID-19 pandemic, sovereign governments expanded their issuance of treasury bills, notes, and bonds to record levels. As central banks subsequently raised policy interest rates from 2022 through 2024 to curb elevated consumer price inflation, sovereign yields climbed from near-zero levels to multi-year highs.
Concurrently, the rapid commercial development of generative artificial intelligence technology since 2023 initiated a massive capital expenditure cycle among global technology enterprises. Building the compute capacity needed to train and run large-scale foundational models requires extensive hardware infrastructure, including specialized graphics processing units (GPUs), high-speed networking gear, hyper-scale data centers, and dedicated electrical power generation facilities.
While top-tier technology firms continue to generate substantial operating cash flows, the sheer magnitude and speed of required AI investments have led corporate treasurers to leverage primary debt markets. By issuing long-dated corporate bonds, these firms can lock in long-term funding structures and preserve liquid cash reserves for tactical operational needs and strategic acquisitions.
Meanwhile, energy markets remain a primary channel for transmitting macroeconomic shocks into global bond pricing. Crude oil price fluctuations directly affect transportation, manufacturing, and consumer price indexes worldwide. When oil prices experience sustained upward momentum, inflation expectations rise across fixed-income trading desks. Higher inflation expectations diminish the real return of fixed-coupon bonds, prompting investors to demand higher yields as compensation for holding long-duration fixed-income securities. The convergence of heavy sovereign bond issuance, expanding corporate debt supply for technology buildouts, and energy market volatility creates a complex environment for global capital allocation.
Reaction
Financial market participants across Asian equity and fixed-income desks responded with heightened caution as bond market pressures built. Institutional fund managers were observed re-balancing portfolios, selectively trimming equity exposures in favor of short-term liquid instruments while waiting for the full terms and pricing of the reported corporate bond offerings to materialize.
Fixed-income strategists noted that the direct competition between investment-grade corporate issuers and sovereign treasuries is forcing primary market dealers to adjust their pricing models. Rather than benchmarking corporate debt purely off sovereign yield curves, dealers must account for the liquidity drain caused by simultaneous large-scale corporate offerings.
Central bank officials across the Asia-Pacific region have not issued immediate formal statements regarding Thursday's trading dynamics, but monetary policy committees are closely tracking the pass-through of rising U.S. Treasury yields and energy prices into local currency values and domestic money market rates. Regional central banks often face pressure to adjust local liquidity conditions when widening yield differentials between U.S. and domestic bonds trigger currency depreciation and capital outflows.
What we don't know yet
Several critical variables surrounding the reported corporate debt issuances and broader bond market pressures remain unresolved:
What to watch
Investors and market analysts are monitoring several key indicators and upcoming decision points to gauge the direction of global bond and equity markets:
This report is based on coverage compiled by CNA detailing Asian stock market declines, sovereign bond market pressures, technology sector corporate debt plans, and oil price developments on Oct. 8, 2026.
How this story was produced
This report was written by The Global Wire newsroom from reporting first published by CNA. We verify the core facts against the original report, write our own account, and add the background and consequences a short wire item leaves out. Drafting is AI-assisted inside an editor-supervised pipeline, and every story is checked for accuracy of attribution, structure and duplication before it appears — full detail in our AI and funding disclosure.
Spotted an error? Tell us at corrections@horizonglobalnews.com and read our corrections policy or editorial standards.

Reader comments
Loading comments…