

Global Equities Retrench as Rising Bond Yields and Oil Prices Reignite Inflation Concerns
Stock markets fell on September 23 as soaring energy costs and rising U.S. Treasury yields eroded risk appetite amidst diplomatic stagnation at the UN General Assembly.
By The Global Wire Newsroom · Reported from CNA
Link preview · horizonglobalnews.com
Global Equities Retrench as Rising Bond Yields and Oil Prices Reignite Inflation Concerns
Stock markets fell on September 23 as soaring energy costs and rising U.S. Treasury yields eroded risk appetite amidst diplomatic stagnation at the UN General Assembly.
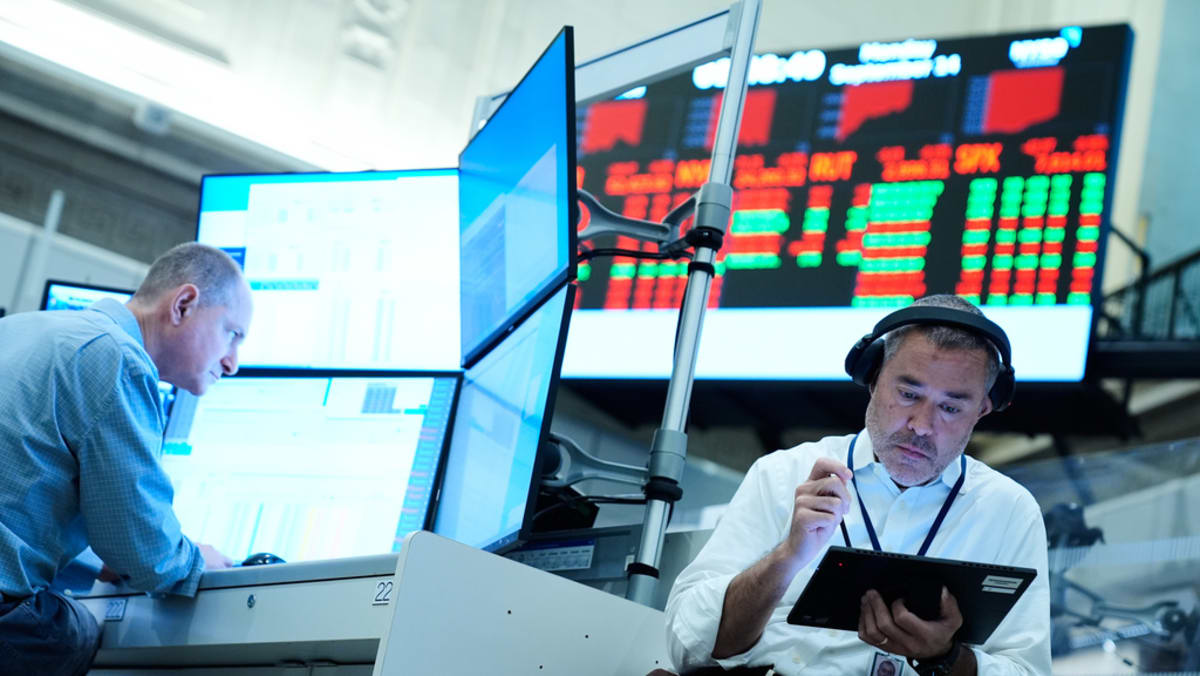
Global equity markets experienced widespread declines on Wednesday, September 23, 2026, as a simultaneous surge in crude oil prices and a sharp jump in U.S. Treasury bond yields rattled financial markets and renewed anxieties over persistent inflation. The market retreat unfolded against the backdrop of high-level diplomatic discussions at the annual United Nations General Assembly in New York, where speeches and bilateral meetings among international leaders provided little immediate evidence of progress toward resolving ongoing instability in the Middle East. The dual pressures of higher energy costs and elevated fixed-income borrowing rates triggered a sell-off in risk assets, interrupting previous market stability and raising fresh questions about the path of global monetary policy and corporate earnings performance.
Key facts
What happened
The trading session on September 23 marked a clear pivot in global financial sentiment, driven by interacting factors across commodity exchanges, sovereign debt markets, and geopolitical arenas, according to reporting by CNA. After experiencing several sessions of price declines, crude oil benchmarks reversed course sharply. The sudden upward trajectory in energy prices quickly reverberated through fixed-income markets, where U.S. Treasury yields experienced a pronounced upward spike. Investors quickly priced in the potential for sustained headline inflation, which reduces the real returns on fixed-income instruments and elevates short- and long-term capital costs.
As government bond yields climbed, equity markets in North America and across international centers came under immediate selling pressure. Higher bond yields reduce the relative attractiveness of stock valuations, particularly for growth and technology sectors whose projected cash flows are discounted at higher discount rates. The selling was further compounded by market reactions to ongoing diplomatic proceedings in New York, where heads of state and international delegations gathered for the high-level debate of the United Nations General Assembly. Statements delivered by world leaders offered few concrete indications of near-term resolutions to Middle East tensions, sustaining a risk premium in global energy markets and reinforcing uncertainty among international investors.
Why it matters
The simultaneous rise of sovereign bond yields and energy prices creates a classic macroeconomic headwind for major economies, acting as a double-edged pressure point on both corporate profitability and household purchasing power. Energy costs represent a foundational input across global supply chains, affecting transportation, manufacturing, agriculture, and utility overheads. When crude prices experience sudden spikes, the inflationary impact rapidly transmits into broader consumer price indexes, forcing businesses to choose between absorbing reduced profit margins or passing higher operational costs along to end consumers.
Concurrently, elevated bond yields increase the cost of capital across the financial system. U.S. Treasury yields act as the foundational benchmark for pricing consumer mortgages, corporate debt issuances, commercial lending rates, and international sovereign borrowing. Higher borrowing costs discourage business capital expenditures, slow real estate transactions, and constrain leveraged investment strategies. For financial equity markets, higher risk-free yields alter valuation models, prompting institutional portfolio managers to reallocate capital away from high-beta equities and into fixed-income instruments offering attractive risk-adjusted returns. Furthermore, persistent geopolitical volatility surrounding Middle East energy supply routes complicates central bank strategy, threatening to prolong tight monetary conditions even as economic growth slows.
The background
To understand the significance of the September 23 market moves, it is necessary to examine the broader historical interplay between energy prices, sovereign yield curves, and macroeconomic policy. Over the past decade, financial markets have operated under heightened sensitivity to supply-side inflation shocks. Following severe inflationary spikes in recent years, central banks worldwide—including the U.S. Federal Reserve, the European Central Bank, and the Bank of England—implemented aggressive monetary tightening campaigns, raising benchmark policy rates to multi-year highs to stabilize prices.
In sovereign debt markets, U.S. Treasury yields serve as the ultimate global pricing mechanism for fixed-income assets. When inflation fears resurface, investors demand higher yields to compensate for the diminishing purchasing power of fixed future coupon payments. This dynamic routinely causes bond prices—which move inversely to yields—to fall, creating ripple effects across global banking systems and money markets.
Energy markets play a pivotal role in this equation. Benchmark crude contracts, including North Sea Brent and West Texas Intermediate (WTI), are heavily influenced by physical supply balances, inventory levels, and geopolitical stability in producing regions. The Middle East remains a critical geographic center for global oil production and transit, housing key strategic chokepoints such as the Strait of Hormuz—through which roughly one-fifth of global petroleum flows—and critical Red Sea shipping corridors. Geopolitical instability in these regions historically introduces a risk premium into crude pricing, as market participants hedge against potential supply disruptions or transit blockades.
The United Nations General Assembly, established under the UN Charter in 1945, serves as the principal policy-making and representative organ of the organization. Meeting annually every September at UN Headquarters in New York, the General Assembly gathers leaders from 193 member states to address global security, sustainable development, and international conflicts. While the assembly provides a high-profile diplomatic platform, structural divisions among permanent Security Council members and regional blocs frequently impede rapid consensus on binding peace agreements or international mandates during active crisis periods.
Reaction
In response to the market movements on September 23, institutional investors and market strategists initiated portfolio realignments, reflecting heightened caution over macro uncertainty. Asset managers adjusted duration exposure in fixed-income holdings while paring back allocations in cyclical equity sectors vulnerable to higher input costs and elevated borrowing rates.
While formal public responses from major economic institutions were not issued immediately during the trading session, central bank officials and corporate finance executives continuously monitor sharp moves in bond yields and commodity markets. Monetary policymakers evaluate whether yield spikes reflect changing growth expectations or rising inflation premiums, which directly influences future interest rate decisions. Meanwhile, corporate executives in energy-intensive industries face mounting pressure to hedge fuel commitments and manage debt refinancing schedules under higher interest rate environments. At the United Nations General Assembly, diplomatic delegations, regional alliances, and non-governmental bodies face ongoing expectations from international markets and civil society to establish credible pathways toward conflict resolution and economic stability in impacted trade corridors.
What we don't know yet
Several critical parameters surrounding the September 23 market decline remain unconfirmed or subject to further developments. The available reporting leaves exact quantitative details unstated, such as the specific percentage drops across major equity indexes like the S&P 500, Dow Jones Industrial Average, or Nasdaq Composite, as well as European and Asian equity benchmarks.
Additionally, the exact magnitude of the move in bond yields—specifically the basis-point shifts in 2-year, 10-year, and 30-year U.S. Treasury notes—was not specified in initial summaries provided by reporting outlets. In energy markets, while crude prices reversed several sessions of declines, the precise closing prices per barrel for North Sea Brent or West Texas Intermediate crude remain unverified in the immediate account. From a policy perspective, it is unclear whether central bank governors will view this single-day jump in yields and oil prices as a transitory market fluctuation or as evidence of structural inflation persistence that warrants keeping policy rates higher for an extended period. Finally, the long-term diplomatic impact of discussions taking place behind closed doors at the UN General Assembly remains to be seen.
What to watch
In the coming days and weeks, market observers and institutional investors should monitor several key milestones to gauge whether September 23 marked a temporary market blip or the start of a broader structural correction.
First, upcoming macroeconomic data releases—specifically Consumer Price Index (CPI), Producer Price Index (PPI), and Personal Consumption Expenditures (PCE) reports in the United States, Eurozone, and major Asian economies—will provide crucial evidence regarding underlying inflation trends. Second, energy market fundamentals will depend heavily on weekly inventory reports from the U.S. Energy Information Administration (EIA) and upcoming production policy announcements from the OPEC+ alliance. Third, yield curve movements across U.S. Treasuries, German Bunds, and Japanese Government Bonds will reveal whether fixed-income markets are settling into higher yield ranges. Fourth, ongoing bilateral diplomatic meetings, emergency Security Council sessions, and official communique releases concluding the United Nations General Assembly in New York will show whether international mediation efforts can ease geopolitical risk in the Middle East.
This news report is based on coverage provided by CNA.
How this story was produced
This report was written by The Global Wire newsroom from reporting first published by CNA. We verify the core facts against the original report, write our own account, and add the background and consequences a short wire item leaves out. Drafting is AI-assisted inside an editor-supervised pipeline, and every story is checked for accuracy of attribution, structure and duplication before it appears — full detail in our AI and funding disclosure.
Spotted an error? Tell us at corrections@horizonglobalnews.com and read our corrections policy or editorial standards.

Reader comments
Loading comments…