

Backblaze Top-Line Expansion Accelerates as B2 Storage Offsets Legacy Backup Drag
Financial analysis by Bashar Issa indicates that NASDAQ-listed Backblaze is seeing faster revenue growth as its enterprise B2 Cloud Storage segment expands its share of total sales.
By The Global Wire Newsroom · Reported from Bashar Issa
Link preview · horizonglobalnews.com
Backblaze Top-Line Expansion Accelerates as B2 Storage Offsets Legacy Backup Drag
Financial analysis by Bashar Issa indicates that NASDAQ-listed Backblaze is seeing faster revenue growth as its enterprise B2 Cloud Storage segment expands its share of total sales.
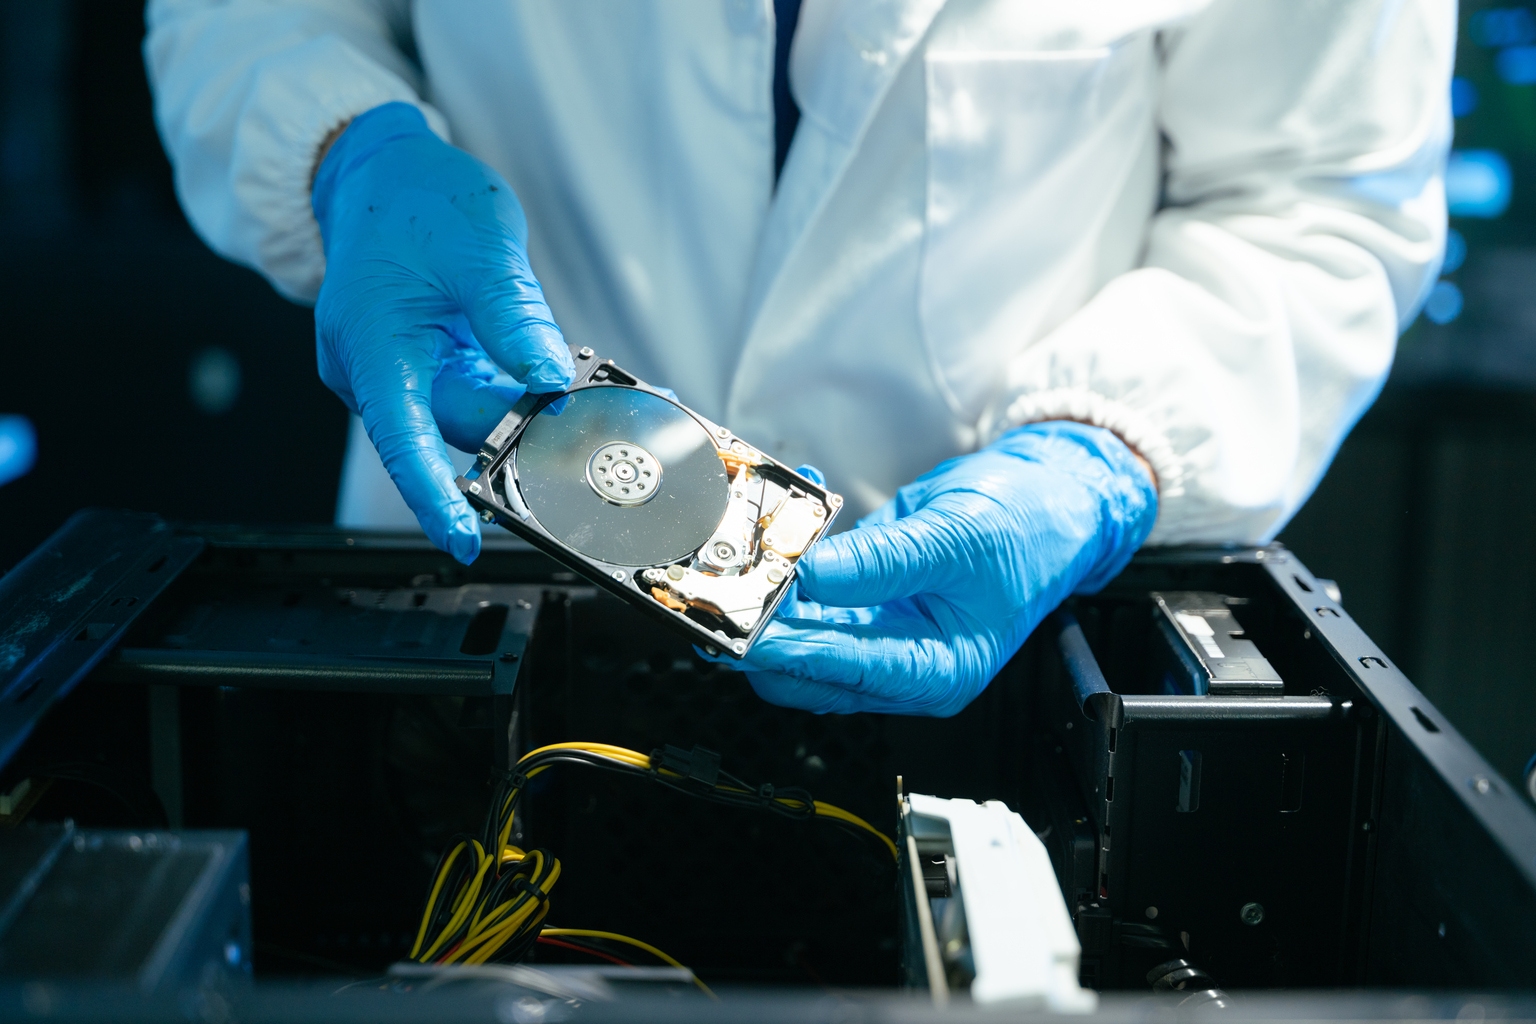
In financial market commentary released on August 25, 2026, market research publication Bashar Issa reported that cloud storage provider Backblaze Inc. is experiencing a notable operational shift, marked by accelerating total revenue growth driven by its enterprise-focused B2 Cloud Storage business segment. According to the analysis, structural growth headwinds long associated with the company’s legacy Computer Backup division are diminishing in relative impact as consumption-based cloud storage commands an increasing share of overall sales. The transition has led to an upgraded financial outlook for the company, whose equity trades on the NASDAQ exchange under the ticker symbol BLZE, with the outlet assigning the stock a Strong Buy recommendation based on improving fundamental revenue momentum.
Key facts
What happened
According to analysis published by Bashar Issa, Backblaze Inc. has reached a pivot point in its financial performance, characterized by a fundamental shift in its revenue mix. For several fiscal quarters following its public market debut, the company's overall top-line growth rate reflected a structural tension between two distinct business lines operating at different growth velocities: the mature Computer Backup division and the high-growth B2 Cloud Storage infrastructure segment.
The analysis emphasizes that the operational friction created by the slower-expanding desktop backup line is losing its capacity to dampen company-wide financial performance. Historically, because the backup division represented the foundational bulk of recurring annual revenue, its modest single-digit or low double-digit expansion rate acted as a quantitative weight on consolidated growth metrics. However, as the B2 Cloud Storage segment has sustained higher percentage growth rates over successive quarters, its contribution to absolute revenue has expanded significantly.
As a mathematical consequence of this segment rebalancing, B2 Cloud Storage now exerts a dominant influence on overall corporate expansion. The accelerating contribution from consumption-based cloud storage is outstripping the slower baseline growth of consumer and small-business desktop backup plans. Consequently, consolidated top-line growth is trending upward, signaling to financial markets that the historical drag imposed by the legacy business is effectively dissipating. Based on this structural inflection, the reporting from Bashar Issa concludes that Backblaze equity presents an attractive risk-reward profile for public market investors, supporting a Strong Buy classification.
Why it matters
The re-acceleration of Backblaze's top-line revenue carries meaningful implications for cloud software investors, enterprise data storage buyers, and broader market evaluations of hybrid SaaS-IaaS corporate models. In public software markets, companies undergoing a structural business transition—moving from fixed-fee consumer subscriptions to scalable consumption-based infrastructure—frequently experience significant valuation multiple re-ratings once the infrastructure segment surpasses critical revenue thresholds.
For investors, the fading of the "backup drag" directly addresses a long-standing structural concern regarding Backblaze's long-term growth ceiling. Consumer and desktop computer backup services operate in a highly mature market characterized by fixed monthly or annual pricing per device, rising storage consumption per user, and intense competition from operating system vendors like Apple and Microsoft. These dynamics limit pricing power and compress gross margins over time. In contrast, B2 Cloud Storage functions as an Infrastructure-as-a-Service (IaaS) platform, where customers pay for exact gigabytes stored and bandwidth utilized. This model generates higher net revenue retention rates, as enterprise customers, software developers, and media production companies continuously scale their data footprints.
Furthermore, an accelerating top line improves Backblaze's operating leverage. Cloud infrastructure providers incur substantial fixed capital expenditures to deploy custom server storage hardware, network routing infrastructure, and data center facilities. When revenue growth accelerates, high fixed server rack costs are distributed across a wider base of billed storage bytes, improving gross margin profiles and accelerating the path toward sustained GAAP operational profitability.
For enterprise buyers and software developers evaluating cloud object storage alternatives to dominant hyperscalers, Backblaze’s strengthening corporate revenue profile provides institutional validation. A financially accelerating independent cloud provider is better positioned to reinvest capital into network reliability, multi-region redundancy, enhanced developer APIs, and security compliance certifications, ensuring its viability as a competitive, low-cost alternative in the cloud ecosystem.
The background
To contextualize the evolution of Backblaze Inc., it is necessary to examine the company's origins, technology architecture, and public market history. Founded in 2007 by Brian Wilson, Gleb Budman, and a core team of tech entrepreneurs, Backblaze established its headquarters in San Mateo, California. The company initially gained widespread recognition within the computer technology sector for its direct-to-consumer online backup software, which offered unlimited personal computer data backup for a low flat subscription fee.
To make unlimited backup economically viable, Backblaze rejected expensive commercial enterprise storage arrays and instead engineered its own proprietary, open-source server hardware, known as "Backblaze Storage Pods." By assembling high-density hard drive chassis using off-the-shelf consumer components and developing custom cloud storage file systems, the company reduced storage capital costs by an order of magnitude compared to traditional IT vendor pricing.
In 2015, Backblaze leveraged this proprietary storage technology stack to launch B2 Cloud Storage, entering the enterprise Infrastructure-as-a-Service market. B2 was designed as an object storage platform fully compatible with the industry-standard Amazon Web Services Simple Storage Service (AWS S3) Application Programming Interface (API). By offering S3-compatible cloud storage at a fraction of hyperscaler list prices—often charging roughly one-fifth the storage fees of AWS S3 and offering reduced data egress charges—Backblaze attracted developers, systems integrators, and mid-market enterprises seeking to cut cloud infrastructure bills.
In November 2021, Backblaze completed its initial public offering on the NASDAQ stock exchange under the ticker symbol BLZE. Following its debut, equity analysts routinely divided the company's operating profile into two distinct halves: the legacy Computer Backup unit, which generated stable, high-margin subscription cash flows but experienced modest growth, and B2 Cloud Storage, which demonstrated rapid market adoption but required ongoing infrastructure investments. As macroeconomic conditions tightened and cloud spending moderated across 2022 and 2023, public market investors closely monitored the tipping point at which B2’s financial weight would outweigh the growth drag of the computer backup segment.
Reaction
The positive coverage and Strong Buy thesis published by analyst outlet Bashar Issa represents an optimistic perspective on Backblaze's market trajectory. Equity research commentary of this nature typically resonates with individual retail traders and institutional micro-cap software investors seeking value opportunities in secondary cloud infrastructure stocks.
While the primary summary from Bashar Issa outlines the bullish investment thesis based on accelerating top-line performance, formal public responses from Backblaze management or counter-analyses from Wall Street investment banking firms were not detailed in the brief report. Typically, when independent research outlets highlight fundamental segment transitions, market participants examine subsequent trading volume in NASDAQ:BLZE shares, changes in institutional short interest, and updates to sell-side consensus earnings models.
In broader technology investment forums, analysts frequently debate whether independent storage providers can maintain hyper-growth against competing low-cost object storage platforms, such as Wasabi Technologies and Cloudflare R2, both of which aggressively target hyperscaler price premiums. Management teams at mid-tier cloud firms generally address structural segment shifts during scheduled quarterly earnings calls and investor conferences.
What we don't know yet
Despite the optimistic outlook detailed by Bashar Issa, several key quantitative and strategic data points remain unstated in the available summary reporting:
What to watch
To evaluate whether the fading backup drag translates into long-term corporate value creation, market participants should monitor several concrete, verifiable milestones:
This news report is based on financial analysis and market commentary originally published by Bashar Issa on August 25, 2026.
How this story was produced
This report was written by The Global Wire newsroom from reporting first published by Bashar Issa. We verify the core facts against the original report, write our own account, and add the background and consequences a short wire item leaves out. Drafting is AI-assisted inside an editor-supervised pipeline, and every story is checked for accuracy of attribution, structure and duplication before it appears — full detail in our AI and funding disclosure.
Spotted an error? Tell us at corrections@horizonglobalnews.com and read our corrections policy or editorial standards.




Reader comments
Loading comments…