

Singapore Court Rejects Mother's $1M Property Claim, Ruling Transfer Was a Loan
A Singapore judicial ruling denying a parent property ownership after she provided over $1 million for her daughter's home highlights major legal and tax risks in family real estate financing.
By The Global Wire Newsroom · Reported from Tan Ooi Boon
Link preview · horizonglobalnews.com
Singapore Court Rejects Mother's $1M Property Claim, Ruling Transfer Was a Loan
A Singapore judicial ruling denying a parent property ownership after she provided over $1 million for her daughter's home highlights major legal and tax risks in family real estate financing.
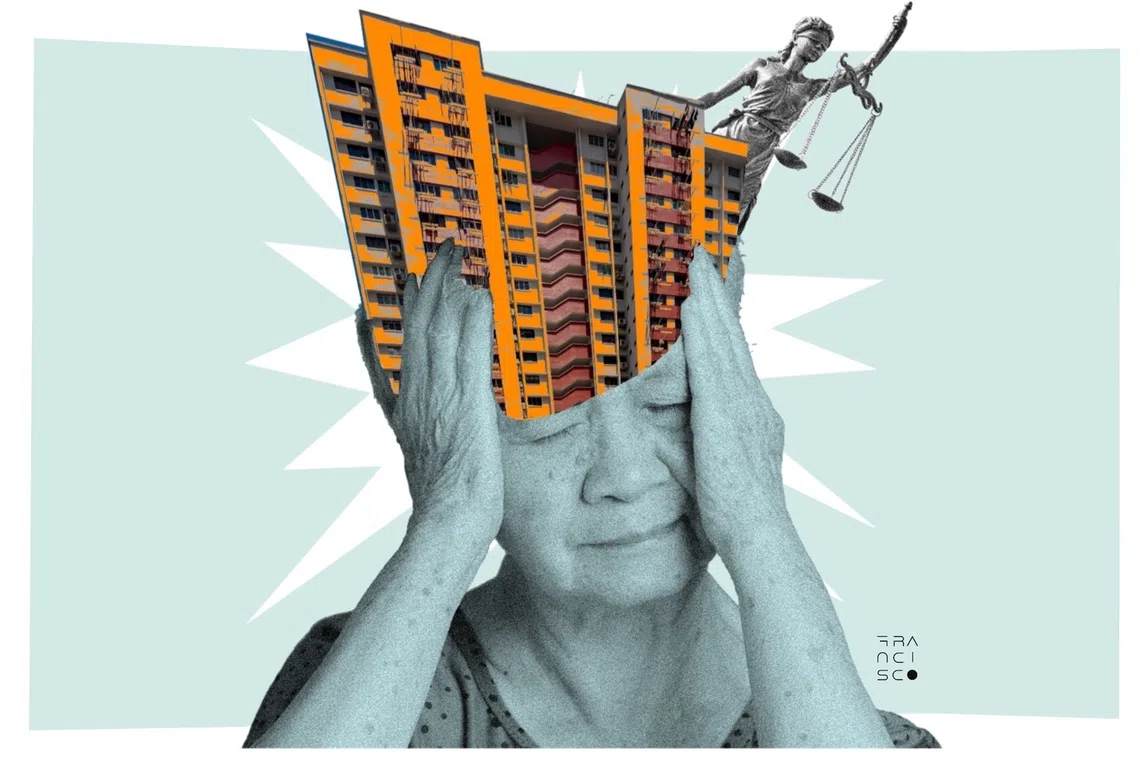
A Singapore court has dismissed a mother's legal petition seeking a beneficial ownership stake in a residential property registered under her daughter's name, ruling that her financial contribution of more than $1 million constituted a personal loan rather than an equity investment or resulting trust interest. The judgment underscores the severe legal and tax hazards confronting parents who inject substantial capital into property purchases titled under family members without executing formal trust documents or clear contractual agreements. By categorizing the seven-figure financial outlay as a debt obligation rather than an equitable share in the real estate, the court left the mother without proprietary rights over the home, demonstrating that monetary assistance among relatives cannot automatically be converted into real estate ownership when interpersonal relationships collapse.
Key facts
What happened
The legal dispute centered on a residential property transaction in which a mother provided over $1 million to assist her daughter in acquiring a home. The property's legal title was placed exclusively in the daughter's name. Following a subsequent breakdown in family relations, the mother initiated legal action in the Singapore courts, seeking a formal declaration that she held a proportionate beneficial interest in the property based on her monetary contribution.
Under established principles of property and equity law, when a person provides purchase money for real estate registered under another individual's name, the judicial system must analyze the original nature of the financial transfer. Courts consider whether the funds were extended as an absolute gift, a personal loan, or a financial contribution intended to create a resulting trust that grants the provider a beneficial ownership stake.
In evaluating the evidence, the court examined contemporaneous documentation, bank records, and communications between the mother and daughter at the time the property was acquired. The court determined that the mother failed to demonstrate a clear mutual intention to create a trust or share equitable ownership of the home when the capital was transferred. Instead, the available evidence established that the $1 million outlay functioned as a debt obligation owed by the daughter.
As a result, the court denied the mother's claim to be recognized as a beneficial owner of the property. While the ruling leaves open the mother's legal right as a creditor to demand repayment of the $1 million loan principal, it completely terminates her claim to the property's title, capital appreciation, or occupancy rights.
Why it matters
The judicial outcome carries significant implications for family asset management, wealth transfer planning, and real estate market practices. In high-value real estate markets like Singapore, parents frequently co-fund or fully finance home purchases for adult children. However, conflating financial generosity with equitable property ownership creates acute legal risks when transactions lack formal documentation.
From a financial perspective, the legal distinction between a loan and a beneficial trust interest radically alters the financial recovery available to the contributing parent. If a contribution is recognized as a beneficial trust interest, the parent owns a percentage share of the physical asset and directly benefits from long-term real estate appreciation. In contrast, when a court classifies the funds as a loan, the parent is restricted to recovering only the fixed principal sum extended, typically without sharing in property value growth. Furthermore, recovering a loan debt depends entirely on the borrower's personal solvency, whereas a property owner holds a direct legal claim against the real estate asset itself.
The ruling also highlights potential tax and regulatory pitfalls, particularly concerning Additional Buyer's Stamp Duty (ABSD) regulations. In Singapore, residential property purchases are subject to tiered stamp duty structures designed to manage housing affordability. Citizens acquiring their first residential property face significantly lower stamp duty rates than individuals purchasing second or subsequent properties, who face heavy tax surcharges. Parents who already own real estate sometimes purchase additional properties under the names of adult children who hold no prior real estate to avoid triggering higher ABSD rates.
If a parent subsequently claims beneficial ownership over a child's home in court, such assertions can trigger immediate regulatory scrutiny from revenue authorities. If tax officials determine that an undisclosed trust was formed to evade stamp duty obligations, the parties risk back-dated tax assessments and substantial penalties. Conversely, if no trust exists and the transaction is ruled a loan, the parent loses all capital growth rights while the child remains the sole legal owner.
The background
The legal framework governing family property disputes in Singapore draws heavily from common law doctrines of equity, trusts, and land title registration. Under the Land Titles Act, the registered proprietor listed on the official property title is presumed to be the absolute owner of the land. To challenge this statutory presumption, a claimant who is not named on the title must prove the existence of an equitable trust, such as a resulting trust or a constructive trust.
Historically, common law courts applied the presumption of resulting trust when Person A paid for property registered in the name of Person B, assuming Person B held the property on trust for Person A. However, this presumption was traditionally counterbalanced by the presumption of advancement, which assumed that financial transfers from a parent to a child were intended as absolute gifts. In modern jurisprudence, courts place diminished weight on automatic legal presumptions, focusing instead on objective, contemporaneous evidence showing the true subjective intention of the parties at the exact moment the funds were disbursed.
This legal standard operates within a highly structured real estate environment. Singapore's residential property sector is among the most closely regulated in the world, with government agencies utilizing macroprudential measures, total debt servicing ratios, and progressive ABSD rates to curb speculative investment. Under tax regulations administered by the Inland Revenue Authority of Singapore (IRAS), any creation of a trust over residential property must be formally declared and stamped within statutory timeframes.
Despite these stringent legal frameworks, informal financial arrangements between family members remain widespread. Parents often transfer large sums without executing legal loan contracts, mortgage deeds, or formal trust agreements, relying on familial trust. When family relationships deteriorate, these unwritten arrangements frequently end up in litigation, where courts apply strict evidentiary standards rather than subjective expectations.
Reaction
Although formal public statements from the mother and daughter involved in the suit were not disclosed in initial court reporting, the decision has generated widespread discussion among legal practitioners, private wealth managers, and real estate advisors in Singapore.
Property law specialists have identified the ruling as an important reminder of the strict evidentiary burdens required to establish property trusts. Legal professionals emphasize that courts will not reconstruct informal family financial assistance into property ownership after the fact simply because large sums of money were exchanged. Lawyers strongly advise individuals providing property funding to execute clear contemporaneous documentation—such as formal loan agreements with defined repayment terms or legally registered trust deeds—prior to releasing funds.
Tax and wealth advisory professionals have also highlighted the case as an illustration of the dangers of uncoordinated property structuring. Consultants warn that attempting to hold informal beneficial interests in real estate to manage tax exposure creates unmanageable legal vulnerabilities.
What we don't know yet
Several key operational details and legal aspects of the court's judgment remain unconfirmed in the available reporting:
What to watch
In the coming months, several critical indicators will determine the legal and financial trajectory of this case:
This report is based on original reporting published by The Straits Times and senior law correspondent Tan Ooi Boon.
How this story was produced
This report was written by The Global Wire newsroom from reporting first published by Tan Ooi Boon. We verify the core facts against the original report, write our own account, and add the background and consequences a short wire item leaves out. Drafting is AI-assisted inside an editor-supervised pipeline, and every story is checked for accuracy of attribution, structure and duplication before it appears — full detail in our AI and funding disclosure.
Spotted an error? Tell us at corrections@horizonglobalnews.com and read our corrections policy or editorial standards.




Reader comments
Loading comments…