

Australia Bans Card Surcharges, Prompting Retailers and Cafes to Raise Prices
A nationwide ban on credit and debit card surcharges has forced Australian businesses to absorb payment processing fees or raise list prices amid persistent operating cost pressures.
By The Global Wire Newsroom · Reported from Bloomberg
Link preview · horizonglobalnews.com
Australia Bans Card Surcharges, Prompting Retailers and Cafes to Raise Prices
A nationwide ban on credit and debit card surcharges has forced Australian businesses to absorb payment processing fees or raise list prices amid persistent operating cost pressures.
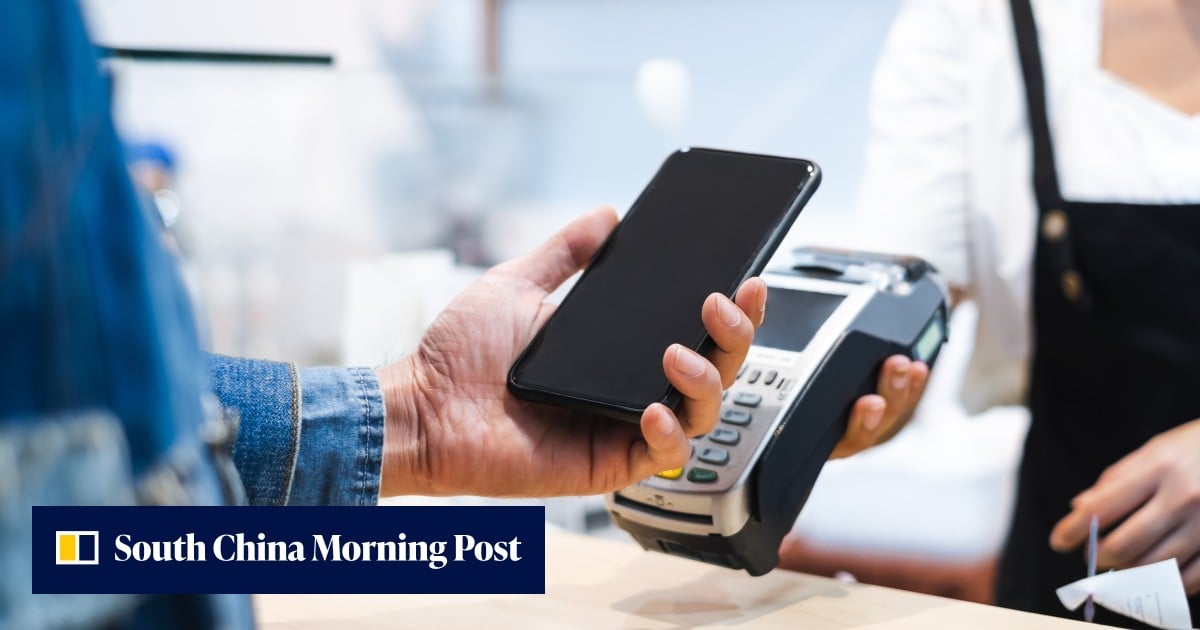
Australia’s retail and hospitality sectors entered a new regulatory era on Oct. 1, 2026, as a broad ban on card payment surcharges came into force across the nation. The policy overhaul, described as one of the most significant shifts in Australia’s payment ecosystem in decades, eliminates the long-standing practice of merchants adding extra fees at checkout for customers paying via debit or credit cards. To cope with the sudden loss of surcharge revenue while remaining responsible for processing costs levied by financial institutions, thousands of cafes, restaurants, and independent retailers have begun raising menu prices and retail sticker tags. The regulatory transition arrives at a challenging juncture for small and medium-sized enterprises, which are already managing sustained operational headwinds driven by elevated utility tariffs, high commercial rents, and rising labor costs.
Key facts
What happened
The enforcement of the card surcharge ban has fundamentally changed how Australian commercial establishments manage transaction expenses at the cash register. Under the prior framework, merchants had the choice to add a percentage fee or flat charge to card transactions to recover the cost of merchant service fees—expenses charged by commercial banks, payment gateways, and card networks like Visa, Mastercard, and Eftpos for processing electronic payments.
With the prohibition now active, businesses can no longer break out processing costs as a separate line item at checkout. According to reporting by Bloomberg, small business owners, including cafe operators, neighborhood grocers, and boutique retailers, are adjusting by embedding payment fees directly into the base price of goods and services. Rather than displaying lower sticker prices and adding a 1 percent to 2 percent fee at the terminal, merchants are repricing standard offerings upward. For instance, hospitality venues that previously added a 15 to 20 cent fee on a tap-and-go coffee order are incorporating those expenses directly into standard menu items, resulting in higher displayed pricing across the board.
This transition requires comprehensive operational updates. Retailers must re-tag physical merchandise, update digital point-of-sale software, and revise printed and online menus. For small enterprises operating on tight cash reserves, the immediate admin load and financial repricing coincide with wider economic strains. Merchants report that absorbing merchant processing rates without adjusting retail prices would instantly erode already narrow operating margins, making baseline price increases unavoidable across urban and regional markets alike.
Why it matters
The elimination of point-of-sale card surcharges carries significant implications for consumer behavior, small business solvency, and the wider macro economy. For consumers, the change provides immediate billing clarity at the register, removing unexpected add-on costs that frequently sparked customer frustration, particularly as tap-and-go mobile wallet payments became the default payment method across Australia. However, because merchants are compensating by raising display prices, consumers may not experience net financial relief; instead, payment processing costs are now hidden within higher overall price levels for goods and services.
For small and medium enterprises, the ban shifts financial risk back onto business balance sheets. When surcharges were permitted, merchants effectively operated with zero net cost for processing digital transactions, as the end user funded the acquirer and scheme fees. Under the new regime, businesses must pay transaction fees out of gross sales revenue. If a business underestimates its transaction volume or fails to adjust baseline prices sufficiently, profit margins will compress further. Conversely, customers who pay with physical cash may now end up subsidizing the electronic payment costs of cardholders, as cash users pay the new, higher base prices that incorporate card processing fees.
From a policy and inflation perspective, the broad-scale repricing of daily purchases like coffee, takeaway food, and convenience items could exert localized upward pressure on consumer price indexes. While the ban aims to curb hidden fees and streamline retail commerce, its immediate secondary effect is a step-change increase in list prices during an period when households remain highly sensitive to living costs.
The background
Australia's approach to payment surcharging has undergone multiple regulatory cycles over the past quarter-century. In 2002, the Reserve Bank of Australia (RBA) introduced pioneering regulations that granted merchants the explicit right to surcharge card transactions. The intent of the original 2002 policy was to enhance market transparency and foster competition among card schemes by allowing merchants to signal the true cost of expensive credit card rewards programs to consumers.
However, over the subsequent decade, widespread consumer complaints emerged regarding "excessive surcharging," where certain industries—most notably commercial airlines, ticketing agencies, and taxi services—charged fees far exceeding the actual cost of card acceptance. In response, the RBA revised its framework in 2016, establishing strict limits enforced by the Australian Competition and Consumer Commission (ACCC). Under the 2016 rules, surcharges were legally capped at the merchant’s true "cost of acceptance," which included interchange fees, card scheme fees, and payment terminal rental costs.
Despite the 2016 caps, friction persisted as Australia rapidly transformed into one of the world's most cashless societies. The widespread adoption of contactless payment technology, mobile devices, and digital wallets accelerated during the COVID-19 pandemic, making card payments the dominant transaction method for everyday purchases. As cash usage plummeted to historical lows, consumers increasingly viewed card surcharges as an unavoidable tax on daily living rather than an optional fee for a premium service.
Australia's ban aligns it with international precedents. The European Union banned credit and debit card surcharges for consumer cards in 2018 under the updated Payment Services Directive (PSD2), and the United Kingdom enacted a matching ban the same year. In those jurisdictions, regulatory authorities accompanied surcharge bans with strict caps on interchange fees to protect merchants from high processing fees charged by card issuing banks.
Reaction
While initial field reporting from Bloomberg highlights the widespread operational shift toward higher shelf prices, formal responses from industry stakeholders highlight the divided perspective on the policy change.
Small business advocacy organizations, such as the Council of Small Business Organisations Australia (COSBOA) and regional chambers of commerce, have consistently voiced concern over merchant service fees charged by financial institutions. Small business representatives emphasize that while eliminating consumer friction is desirable, a surcharge ban without simultaneous reductions in underlying bank transaction fees simply shifts financial burdens onto vulnerable independent businesses. Small business groups argue that smaller vendors lack the bargaining power of major supermarket chains to negotiate lower merchant fee rates with major banks and payment processors.
Conversely, consumer protection organizations, including groups like CHOICE, have long advocated for the abolition of payment surcharges, arguing that processing costs are an inherent cost of doing business in a modern economy and should be built into visible pricing. Consumer groups contend that transparent, all-inclusive pricing prevents surprise fees at the terminal and restores trust in everyday transactions.
Financial institutions and payment acquirers are expected to face scrutiny regarding their fee structures. With surcharges removed, pressure is likely to shift toward the Reserve Bank of Australia and the federal government to further regulate interchange and scheme fees, ensuring that banks do not extract excessive margins from merchants who no longer have the option to pass those costs directly to buyers.
What we don't know yet
Significant uncertainty remains regarding the long-term structural impact of the surcharge ban on merchant costs and consumer behavior:
What to watch
The account presented above is based on reporting published by Bloomberg.
How this story was produced
This report was written by The Global Wire newsroom from reporting first published by Bloomberg. We verify the core facts against the original report, write our own account, and add the background and consequences a short wire item leaves out. Drafting is AI-assisted inside an editor-supervised pipeline, and every story is checked for accuracy of attribution, structure and duplication before it appears — full detail in our AI and funding disclosure.
Spotted an error? Tell us at corrections@horizonglobalnews.com and read our corrections policy or editorial standards.


Reader comments
Loading comments…