

Global Stocks Slide as Energy Prices Surge and Bond Yields Advance Ahead of Central Banks
Equity markets in New York and London declined as rising crude oil prices and escalating sovereign bond yields dampened investor risk appetite ahead of key U.S. and Japanese policy decisions.
By The Global Wire Newsroom · Reported from thestar.com.my
Link preview · horizonglobalnews.com
Global Stocks Slide as Energy Prices Surge and Bond Yields Advance Ahead of Central Banks
Equity markets in New York and London declined as rising crude oil prices and escalating sovereign bond yields dampened investor risk appetite ahead of key U.S. and Japanese policy decisions.
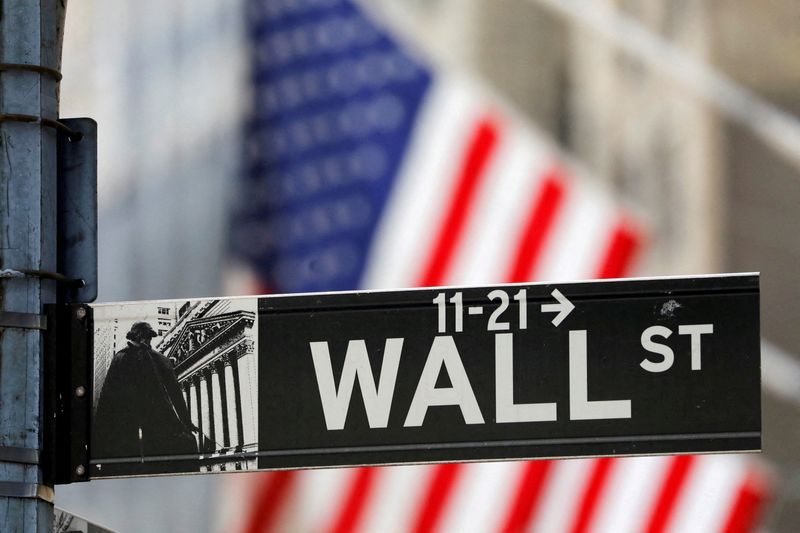
Global financial markets experienced a broad contraction on Monday, Sept. 14, 2026, as falling stock indexes across major international financial hubs reflected growing investor anxiety over surging energy costs and escalating fixed-income yields. Equity benchmarks in New York and London registered widespread losses during Monday trading, driven down by a simultaneous spike in international crude oil prices and a rise in government bond yields. The market retreat highlighted a retrenchment in global risk appetite at a critical calendar juncture, occurring just ahead of high-stakes monetary policy meetings scheduled later in the week by monetary authorities in the United States and Japan.
Key facts
What happened
The trading session on Monday was defined by a synchronized recalibration across major global asset classes. In equity markets spanning New York and London, share prices pulled back as investors responded to dual pressures originating in the commodities and fixed-income sectors. A sudden surge in crude oil prices re-injected cost concerns into financial markets, raising expectations that energy-driven price pressures could linger across national economies.
At the same time, sovereign debt markets faced sell-offs that drove government bond yields higher across key global benchmark maturities. Because bond yields move inversely to bond prices, the yield surge signaled that fixed-income investors were demanding higher yields to hold public debt instruments amid shifting macroeconomic expectations.
The combination of rising energy costs and escalating bond yields directly undermined equity valuations. Higher bond yields increase the risk-free rate of return, making high-risk financial assets such as equities relatively less appealing to institutional asset allocators. Furthermore, elevated yields raise the discount rates applied by financial analysts when calculating the present value of future corporate cash flows, which often leads to downward adjustments in equity pricing, particularly for growth and technology sectors. Combined with the direct burden that higher oil prices place on corporate operating margins and consumer discretionary spending, market participants moved to curtail risk exposure, resulting in broad stock market declines in both North American and European trading sessions.
Why it matters
The simultaneous rise in crude oil prices and government bond yields carries significant structural consequences for financial markets, corporate decision-making, and broader macroeconomic conditions. When energy prices experience a sudden surge, the immediate effect is felt across global supply chains, transportation networks, and manufacturing operations. Higher fuel and feedstock expenses erode corporate profit margins while simultaneously reducing household purchasing power. If sustained, elevated oil prices threaten to reignite broader headline inflation, complicating the path for central banks striving to return price growth to target levels.
Concurrently, rising government bond yields exert a direct tightening effect on financial conditions throughout the broader economy. Sovereign bond yields serve as the fundamental benchmark for setting interest rates on a vast array of financial products, including corporate debt issues, consumer loans, commercial real estate financing, and residential mortgages. When sovereign yields rise, borrowing costs automatically escalate for governments, businesses, and households alike. Higher capital costs can suppress corporate capital expenditures, slow corporate hiring, and constrain mergers and acquisitions activity.
For financial markets, the environment created by concurrent yield spikes and energy price rallies poses a challenge to traditional portfolio diversification strategies. Historically, government bonds have acted as a hedge against stock market downturns. However, when falling bond prices drive yields higher at the exact moment equities are selling off, multi-asset portfolios experience correlated losses across both equity and fixed-income allocations. This dynamic forces asset managers to reduce leverage and reduce exposure to risk assets, compounding selling pressure across global stock markets.
The background
To contextualize the market movements observed in New York and London, it is essential to examine the institutional mechanics governing fixed-income markets, crude oil pricing, and central bank operations. Sovereign debt markets, most notably the United States Treasury market and government bond markets in Western Europe and East Asia, form the bedrock of the international financial system. The yields on these instruments represent the risk-free benchmark rate used globally to price financial risk. Yields fluctuate based on investor expectations regarding inflation, economic growth, public debt supply, and central bank policy rates.
The United States Federal Reserve, through its policy-setting Federal Open Market Committee (FOMC), determines the target range for the federal funds rate, which influences short-term interest rates and broader monetary conditions across the global economy. When the Federal Reserve raises or maintains elevated interest rates to combat inflation, long-dated government bond yields frequently adjust to reflect expected borrowing costs over multi-year horizons.
Similarly, the Bank of Japan (BOJ) plays a crucial role in international capital flows. For decades, Japan maintained ultra-loose monetary policy, including negative short-term interest rates and yield curve control mechanisms, making the Japanese yen a primary funding currency for global carry trades. As the Bank of Japan has gradually shifted toward monetary policy normalization, changes in Japanese yield dynamics and monetary guidance have sent ripple effects across international fixed-income and equity markets.
Energy markets present another layer of systemic sensitivity. Global crude oil prices are driven by complex balances between supply from major producing alliances—such as the Organization of the Petroleum Exporting Countries (OPEC) and its allies—and demand from industrial hubs in North America, Europe, and Asia. Spikes in oil prices historically generate cost-push inflation, creating an economic headwind that reduces economic output while raising general price levels.
Reaction
Following established regulatory frameworks and institutional norms, officials from the Federal Reserve and the Bank of Japan maintained standard pre-meeting quiet periods, during which monetary policymakers refrain from making public comments regarding economic outlooks or interest rate trajectories. Consequently, official policy commentary from central bankers was absent during Monday's trading session.
Market participants, including global investment banks, hedge funds, and institutional asset managers, reacted to the market moves by recalibrating short-term risk metrics and portfolio allocations. Trading desks across London and New York reported defensive positioning, with capital shifting into cash equivalents and defensive market sectors while high-valuation equity sectors experienced heightened selling pressure. Market strategists noted that the confluence of rising energy inputs and yield pressures placed asset allocators in a cautious stance ahead of the pending monetary policy announcements.
What we don't know yet
While the overarching trend of falling stocks, rising yields, and surging oil prices was clear during Monday's session, several critical variables remain unquantified based on available reporting. The precise percentage declines of specific equity indexes—such as the S&P 500, the Dow Jones Industrial Average, the Nasdaq Composite, the FTSE 100, or the Nikkei 225—have not been detailed. Similarly, the exact yield levels reached by key benchmark government bonds, including the 10-year U.S. Treasury note or UK Gilts, remain unstated, as do the specific dollar-per-barrel figures for crude oil benchmarks like Brent Crude or West Texas Intermediate.
Furthermore, the fundamental drivers behind the sudden crude oil surge—whether linked to unexpected geopolitical developments, supply disruptions, or production quota shifts—have not been detailed in initial reporting. Crucially, the outcome of the upcoming policy deliberations by the Federal Reserve and the Bank of Japan, along with their accompanying forward guidance and economic projections, will only become clear once official announcements are released later in the week.
What to watch
In the days immediately following Monday's market downturn, several key events and indicators will determine whether market stability returns or further volatility unfolds:
This news report is based on coverage originally published by The Star (thestar.com.my).
How this story was produced
This report was written by The Global Wire newsroom from reporting first published by thestar.com.my. We verify the core facts against the original report, write our own account, and add the background and consequences a short wire item leaves out. Drafting is AI-assisted inside an editor-supervised pipeline, and every story is checked for accuracy of attribution, structure and duplication before it appears — full detail in our AI and funding disclosure.
Spotted an error? Tell us at corrections@horizonglobalnews.com and read our corrections policy or editorial standards.




Reader comments
Loading comments…